Viral Antigens Market Growth, Outlook and Deep Study of Top Key Players Analysis By Fact.MR
ROCKVILLE, MD /Sept 17, 2026 — The global viral antigens market was valued at USD 2.9 billion in 2025. It is projected to reach USD 3.1 billion in 2026 and USD 6.1 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.0%. The market is anticipated to create an absolute dollar opportunity of USD 3.0 billion between 2026 and 2036.
Note: A Fact.MR blog post associated with the same report series projects a value of USD 5.7 billion by 2035 at the same 7.0% CAGR from the 2025 base of USD 2.9 billion. Figures below follow the primary report page covering the 2026–2036 forecast period.
Get detailed market forecasts, competitive benchmarking, and pricing trends: https://www.factmr.com/connectus/sample?flag=S&rep_id=1305
Key Findings
- Global market size: USD 2.9 billion (2025) → USD 3.1 billion (2026) → USD 6.1 billion (2036).
- CAGR: 7.0% (2026–2036).
- Absolute opportunity: USD 3.0 billion (2026–2036).
- Leading product share (2026): Inactivated Viral Antigens at 35.9%.
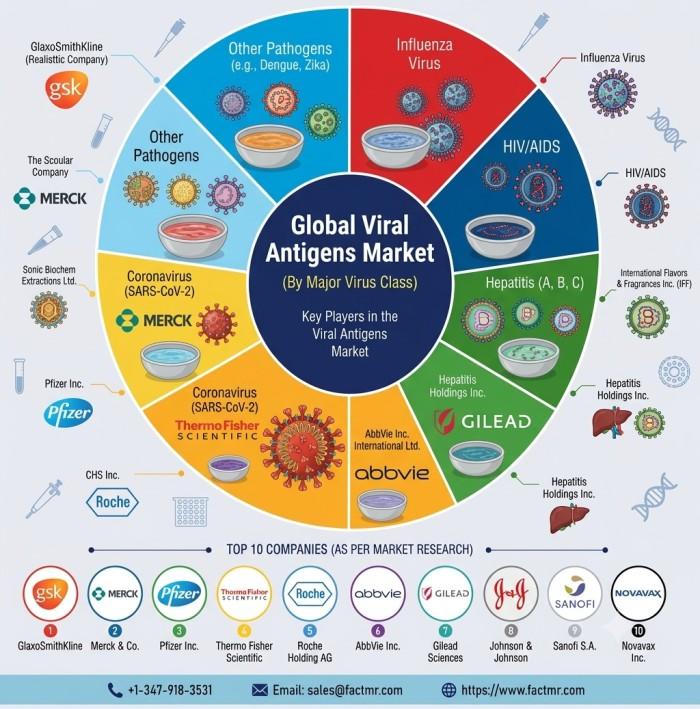
- Leading virus-type share (2026): Influenza Virus Antigens at 28.7%.
- Leading application share (2026): Vaccine Development at 42.3%.
- Fastest-growing country markets: USA (7.6% CAGR) and Mexico (7.1% CAGR).
Viral antigens are purified or recombinant protein components of viruses used as critical raw materials in vaccine development, diagnostic kit manufacturing, and immunology research.
Growth Drivers
- Seasonal and pandemic influenza vaccine production cycles generate recurring procurement demand for influenza virus antigens as primary vaccine components.
- COVID-19 pandemic preparedness investment has expanded coronavirus antigen production capacity and accelerated recombinant antigen platform development.
- Diagnostic kit production growth for infectious diseases, including ELISA and rapid test formats, is generating sustained demand for characterized viral antigen raw materials.
- Recombinant DNA technology adoption is enabling faster, more scalable antigen production compared to traditional egg-based and cell-culture inactivation methods.
- Therapeutic vaccine development programs in oncology and chronic viral infections are creating new demand categories beyond preventive vaccine antigen supply.
- mRNA vaccine platform expansion is creating demand for recombinant spike protein and nucleocapsid antigens as reference standards and assay controls.
- Multiplex diagnostic panel development for respiratory and sexually transmitted infections is increasing the number of antigen targets required per diagnostic kit.
- Emerging market vaccine manufacturing capacity buildout in India, Indonesia, and Brazil is creating new procurement channels for viral antigen raw materials.
Segment Analysis by Product
- Inactivated Viral Antigens: 35.9% of the product segment in 2026. Primary sub-segments are Whole Virus Inactivated Antigens and Chemically Inactivated Antigens.
- Heat Inactivated Viral Antigens: Second position within the product segment.
- Additional categories covered: Recombinant Viral Antigens (including Subunit Antigens, Protein Based Viral Antigens, Peptide Antigens), Split Viral Antigens (Detergent Split Antigens, Purified Surface Antigens), Virus Like Particles (Self Assembled and Recombinant), and Synthetic Viral Antigens (Engineered Antigen Constructs, Epitope Based Antigens).
Recombinant viral antigen production is the technology trend reshaping supply. Traditional inactivated whole-virus antigens require high-biosafety facilities and lengthy cycles; recombinant platforms using mammalian, insect, or microbial expression systems produce characterized proteins faster, at higher purity, and without handling live virus. The transition is most advanced for SARS-CoV-2 antigens. Sino Biological, The Native Antigen Company, and Creative Diagnostics have built recombinant antigen catalogs covering hundreds of viral targets. For influenza and hepatitis, inactivated antigens remain the reference standard, while recombinant alternatives gain share on supply reliability, batch consistency, and reduced biosafety requirements.
Segment Analysis by Technology / Virus Type
- Influenza Virus Antigens: 28.7% of the virus-type segment in 2026. Primary sub-segments: H1N1 Antigens and H3N2 Antigens.
- Coronavirus Antigens: Second-largest category, concentrated in SARS-CoV-2 Antigens and MERS-CoV Antigens.
- Additional coverage includes Hepatitis Virus Antigens (Hepatitis B and C), Human Immunodeficiency Virus Antigens, Human Papillomavirus Antigens, and other viral antigens (Dengue, Zika).
Segment Analysis by Application
- Vaccine Development: 42.3% of the application segment in 2026. Primary sub-segments: Preventive Vaccines and Therapeutic Vaccines.
- Diagnostic Kits: Second-largest category, concentrated in ELISA Based Diagnostics and Rapid Test Kits.
- Additional coverage: Research and Development.
End-use segments: Pharmaceutical and Biotechnology Companies (primary buyer base), Diagnostic Laboratories, and Academic and Research Institutes.
Country-Level Growth Comparison
|
Country |
CAGR (%) |
One-line commercial condition |
|
USA |
7.6 |
Largest market; vaccine R&D concentration, BARDA preparedness procurement, diagnostic manufacturing (Abbott, Hologic, Roche), NIH NIAID research grants. |
|
Mexico |
7.1 |
Vaccine manufacturing expansion (Birmex), diagnostic laboratory growth, COFEPRIS regulatory alignment. |
|
Germany |
6.8 |
BioNTech and CureVac mRNA programs, Siemens Healthineers and Roche diagnostics, Max Planck and Helmholtz virology research. |
|
France |
6.7 |
Sanofi Pasteur vaccine production (Lyon), bioMérieux diagnostics (Marcy-l’Étoile), Institut Pasteur research. |
|
UK |
6.5 |
Oxford Vaccine Group and AstraZeneca programs, The Native Antigen Company headquarters, UKHSA reference laboratories. |
|
South Korea |
6.4 |
SK Bioscience and Samsung Biologics vaccine production, Seegene and SD Biosensor diagnostics, KDCA surveillance. |
|
Japan |
6.2 |
Influenza vaccine production (Denka, KM Biologics, Takeda), Sysmex/Fujirebio/Sekisui diagnostics, NIID reference standards. |
North America accounts for a large share of global demand. Europe shows stable demand. Asia Pacific demand is led by South Korea and Japan.
Competitive Landscape
Leading companies include:
- Merck KGaA
- Creative Diagnostics
- ProSpec-Tany Technogene Ltd.
- The Native Antigen Company Ltd.
- Sino Biological Inc.
- Vircell S.L.
- BioVision, Inc.
- Thermo Fisher Scientific Inc.
- RayBiotech Inc.
- ZeptoMetrix Corporation
Merck KGaA leads through its broad life science reagent portfolio. Specialized suppliers (Sino Biological, The Native Antigen Company, Creative Diagnostics) are capturing share through catalog depth and rapid custom antigen development. Competitive differentiators are antigen catalog breadth, recombinant production platform capability, custom antigen development speed, and regulatory documentation quality. Post-pandemic investment in recombinant capacity has increased competitive intensity.
Recent Developments
- January 2026 – Merck KGaA: Expanded recombinant viral antigen catalog to over 500 targets, including new respiratory syncytial virus and mpox antigen products.
- February 2026 – The Native Antigen Company Ltd.: Announced a pandemic response antigen production platform capable of delivering characterized reference antigens within 6 weeks of novel pathogen sequence availability.
- 2025 – Creative Diagnostics: Launched a rapid custom viral antigen production service delivering milligram-scale characterized proteins within 4 weeks.
- 2025 – ProSpec-Tany Technogene Ltd.: Achieved ISO 13485 certification for its viral antigen manufacturing facility, enabling supply of GMP-grade materials for IVD and vaccine production.
- August 2025 – Thermo Fisher Scientific (blog reference): Announced expansion of its viral antigen portfolio for next-generation diagnostic kits targeting respiratory viruses.
- June 2024 – Sino Biological (blog reference): Launched a new range of recombinant viral antigens for emerging pathogens.
Restraints
- Biosafety level requirements for handling live and inactivated viral material create facility cost and regulatory compliance overhead for antigen manufacturers.
- Antigen stability and cold chain logistics challenges increase distribution cost and limit shelf life for temperature-sensitive viral antigen products.
- Concentration of antigen production expertise among a small number of specialized suppliers creates supply chain vulnerability for downstream vaccine and diagnostic manufacturers.
How to Choose
Procurement and R&D teams evaluating viral antigen suppliers should apply the following criteria drawn from the report’s competitive and technical analysis:
1. Confirm recombinant production platform capability (mammalian, insect, or microbial expression) versus traditional inactivation methods for the required virus type.
2. Evaluate catalog breadth and custom development speed (e.g., milligram-scale characterized proteins within 4 weeks or pandemic-platform delivery within 6 weeks of sequence availability).
3. Verify regulatory documentation quality and certifications such as ISO 13485 for GMP-grade materials intended for IVD or vaccine use.
4. Assess batch consistency, purity, and supply reliability, particularly for influenza and hepatitis reference standards where inactivated antigens remain preferred.
5. Review geographic reach and distribution access relative to end-use locations (pharmaceutical/biotechnology companies, diagnostic laboratories, academic institutes).
6. Align antigen specifications with downstream application requirements (preventive/therapeutic vaccines, ELISA/rapid-test kits, or research-grade reference materials).
Report Scope
The Fact.MR report (FACT1305MR, 170 pages, 48 tables, 141 figures, published 27 May 2026) covers the global viral antigens market by product (inactivated, heat-inactivated, recombinant, split, virus-like particles, synthetic), virus type (influenza, coronavirus, hepatitis, and others), application (vaccine development, diagnostic kits, research and development), end use, and region for the forecast period 2026 to 2036. Quantitative units: USD 3.1 billion to USD 6.1 billion at a CAGR of 7.0%. Methodology combines secondary research (120-plus sources), primary interviews (25-plus), and demand-side modeling across 30-plus countries.
Explore More Related Studies Published by Fact.MR Research
Adult Stem Cells Market- https://www.openpr.com/news/4634485/adult-stem-cells-market-worth-usd-42-2-bn-by-2036-usa-tops-global
Cuffless BP Monitor Market- https://www.openpr.com/news/4634487/cuffless-bp-monitor-market-worth-usd-3-700-mn-by-2036-usa-tops
DNA Encoded Library Market- https://www.openpr.com/news/4634489/dna-encoded-library-market-worth-usd-5-9-bn-by-2036-south-korea
DNA Repair Drugs Market- https://www.openpr.com/news/4634491/dna-repair-drugs-market-worth-usd-27-7-bn-by-2036-usa-tops-global
Women's T-Shirts Market- https://www.openpr.com/news/4634493/women-s-t-shirts-market-worth-usd-181-7-bn-by-2036-usa-tops
About Fact.MR
Fact.MR is a global market research and consulting firm, trusted by Fortune 500 companies and emerging businesses for reliable insights and strategic intelligence. With a presence across the U.S., UK, India, and Dubai, we deliver data-driven research and tailored consulting solutions across 30+ industries and 1,000+ markets. Backed by deep expertise and advanced analytics, Fact.MR helps organizations uncover opportunities, reduce risks, and make informed decisions for sustainable growth.
- Contact Us -
11140 Rockville Pike, Suite 400, Rockville,
MD 20852, United States
Tel: +1 (628) 251-1583 | sales@factmr.com
Flag: The quote attributed to analyst S.N. Jha is sourced directly from published commentary on the report page and requires standard PR media sign-off before official press wire dissemination.

 English
 Arabic
 French
 Spanish
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek