Peripheral Vascular Devices Market Growth Through Catheter-Based Intervention
For decades, the treatment of vascular disease was strongly associated with major surgical intervention. That picture is changing. As clinicians increasingly favor catheter-based approaches and device technologies become more precise, the treatment journey is moving toward interventions that can restore blood flow while limiting procedural burden. This broader change is creating sustained momentum for the Peripheral Vascular Devices Market.
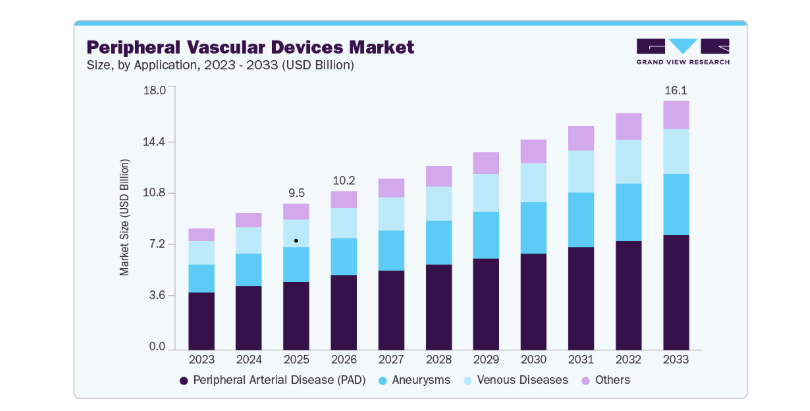
The global market was valued at USD 9.5 billion in 2025 and is projected to reach USD 16.1 billion by 2033, expanding at a 6.6% CAGR from 2026 to 2033. North America accounted for 47.1% of global revenue in 2025, while Asia Pacific is expected to record the fastest growth during the forecast period. Peripheral stents represented 22.2% of the market, PAD accounted for 46.6% by application, and hospitals held a 40.5% end-use share in 2025.
A Larger Patient Pool Is Changing the Treatment Landscape
The first force reshaping the market is the growing burden of peripheral arterial disease and other vascular conditions. Aging populations, diabetes, obesity, smoking, and other risk factors are contributing to a larger population requiring vascular diagnosis and management. As more patients are diagnosed, demand is also shifting toward interventions that can restore circulation without the recovery burden associated with open surgery.
Download a free sample report or claim your copy of this full market intelligence report
A few of the market indicators demonstrate the scale of this opportunity:
- PAD accounted for 46.6% of application revenue in 2025.
- Peripheral stents represented 22.2% of the type segment.
- Hospitals contributed 40.5% of end-use revenue.
- The global market is projected to reach USD 16.1 billion by 2033.
Stents Have the Lead, but the Competitive Story Is Broader
Peripheral stents remain one of the most important product categories, accounting for a significant share of the market in 2025. Their continued adoption is supported by the need to reopen narrowed or blocked arteries and maintain vessel patency following intervention.
At the same time, the most interesting innovation may be happening around the stent.
Drug-eluting technologies are designed to combine mechanical support with drug delivery. Bioresorbable scaffolds introduce another approach by providing temporary vessel support before gradually resorbing. Intravascular lithotripsy is addressing heavily calcified lesions, while atherectomy and thrombectomy systems target plaque and clot-related challenges. Recent developments illustrate how quickly this technology environment is evolving. Grand View Research highlights continued innovation in drug-coated balloons, drug-eluting stents, bioresorbable scaffolds, and intravascular lithotripsy technologies.
The market is consequently moving from a question of “Which device is used?” toward “Which combination of technologies is best suited to this lesion and procedure?”
Accessories Could Become an Increasingly Important Growth Engine
The smaller components of a vascular procedure can be easy to overlook, but they are becoming strategically important as interventions grow more complex. Peripheral accessories are expected to register the fastest growth among type segments.
Guidewires, closure devices, access systems, and other supporting products help physicians reach the treatment site, deliver the primary device, and complete the procedure safely. As more procedures shift toward catheter-based intervention, the need for these supporting technologies can increase alongside the primary treatment devices.
This creates a layered market opportunity:
More procedures → greater device complexity → greater reliance on supporting accessories → broader portfolio demand
That is an important distinction because market growth may not be captured only by manufacturers of high-value stents and grafts. Companies with strong accessory portfolios can also benefit from rising procedural volumes.
Clinical Evidence Has Become a Competitive Currency
Medical device innovation does not end at the launch stage. New technologies must earn clinical acceptance, and this makes trials, studies, and regulatory milestones an important part of competitive positioning.
Manufacturers are increasingly investing in clinical programs to demonstrate safety, effectiveness, deliverability, durability, and long-term benefits. These programs can support regulatory approval while also providing physicians with evidence needed to evaluate newer technologies.
The industry's progression increasingly follows:
Prototype → clinical study → regulatory review → physician adoption → wider commercialization
Grand View Research identifies increasing clinical trials and studies as a significant market driver, noting that evidence generation can accelerate development and help address unmet needs in peripheral vascular treatment.
This also helps explain why companies with strong research capabilities and established regulatory expertise have an advantage when introducing next-generation devices.
Hospitals Still Lead, but the Procedure Location Is Evolving
Hospitals remained the largest end-use segment in 2025 because they provide specialized vascular teams, advanced imaging, procedural infrastructure, and the ability to manage complex patients. However, the growth of ambulatory surgical centers points toward a more distributed model of procedural care. As minimally invasive interventions become more efficient and patient recovery times decrease, selected vascular procedures can increasingly be considered for outpatient settings.
That does not eliminate the importance of hospitals. Instead, it creates a two-speed market in which hospitals remain essential for complex cases while ambulatory settings gain relevance for appropriate lower-risk interventions.
The shift can be summarized as:
Complex intervention → hospital infrastructure
Streamlined minimally invasive procedure → increasing outpatient potential
Grand View Research identifies ambulatory surgical centers as the fastest-growing end-use segment.
North America Leads, While Asia Pacific Accelerates
North America held the largest regional position in 2025, accounting for 47.1% of global revenue. The U.S. remains the largest country market, supported by advanced healthcare infrastructure, vascular intervention capabilities, clinical research, and continued device innovation. Asia Pacific presents a different growth story. The region is expected to record the fastest CAGR through 2033 as healthcare infrastructure expands, awareness of vascular diseases improves, and access to minimally invasive therapies increases. India is particularly notable, with its peripheral vascular devices market projected to reach USD 786.3 million by 2033 at an 11.6% CAGR.
Europe also represents a substantial opportunity, with its market projected to reach USD 4.01 billion by 2033, growing at 6.3% from 2026 to 2033.
The regional balance is therefore becoming more interesting: North America provides scale and maturity, while Asia Pacific provides acceleration and expansion potential.
Technology, Partnerships, and Portfolio Expansion
The competitive landscape is increasingly shaped by companies that can combine device innovation with clinical evidence, regulatory expertise, and broad procedural portfolios. The market includes Abbott, Koninklijke Philips N.V., Edwards Lifesciences Corporation, Medtronic, Teleflex Incorporated, Boston Scientific Corporation, BD, Terumo Corporation, W. L. Gore & Associates, Inc.
Strategic activity is also changing the competitive structure. Acquisitions and collaborations allow established medical device companies to add specialized vascular technologies, enter adjacent intervention categories, or strengthen their geographic reach.
This means competitive advantage is increasingly built across several layers:
- advanced device engineering,
- clinical and regulatory capabilities,
- physician relationships,
- complementary product portfolios,
- and global commercialization networks.
What the Next Phase Could Look Like
The Peripheral Vascular Devices Market is moving toward a more integrated model of vascular intervention. Instead of a single device solving a single problem, physicians increasingly have access to a connected set of technologies designed around diagnosis, navigation, lesion preparation, treatment, and post-procedure management.
Better diagnosis → earlier intervention → more precise devices → minimally invasive treatment → faster procedural pathways
That progression is likely to remain central to market growth. Peripheral stents will continue to be important, but the longer-term opportunity is spreading across balloons, catheters, plaque-modification devices, thrombectomy systems, accessories, and other technologies designed for increasingly complex vascular conditions. The industry's future will ultimately depend on how effectively manufacturers can combine clinical evidence, technological precision, procedural efficiency, and patient-centered care into the next generation of vascular devices.
About us:
Grand View Research, a market research and consulting company, provides syndicated research reports, customized research reports, and consulting services. Grand View Research database is used by the world's renowned academic institutions and Fortune 500 companies to understand the global and regional business environment. Our database features thousands of statistics and in-depth analysis on 46 industries in 25 major countries worldwide.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek