Augmented Reality in Manufacturing Market Growth Opportunities and Regional Outlook 2025–2031
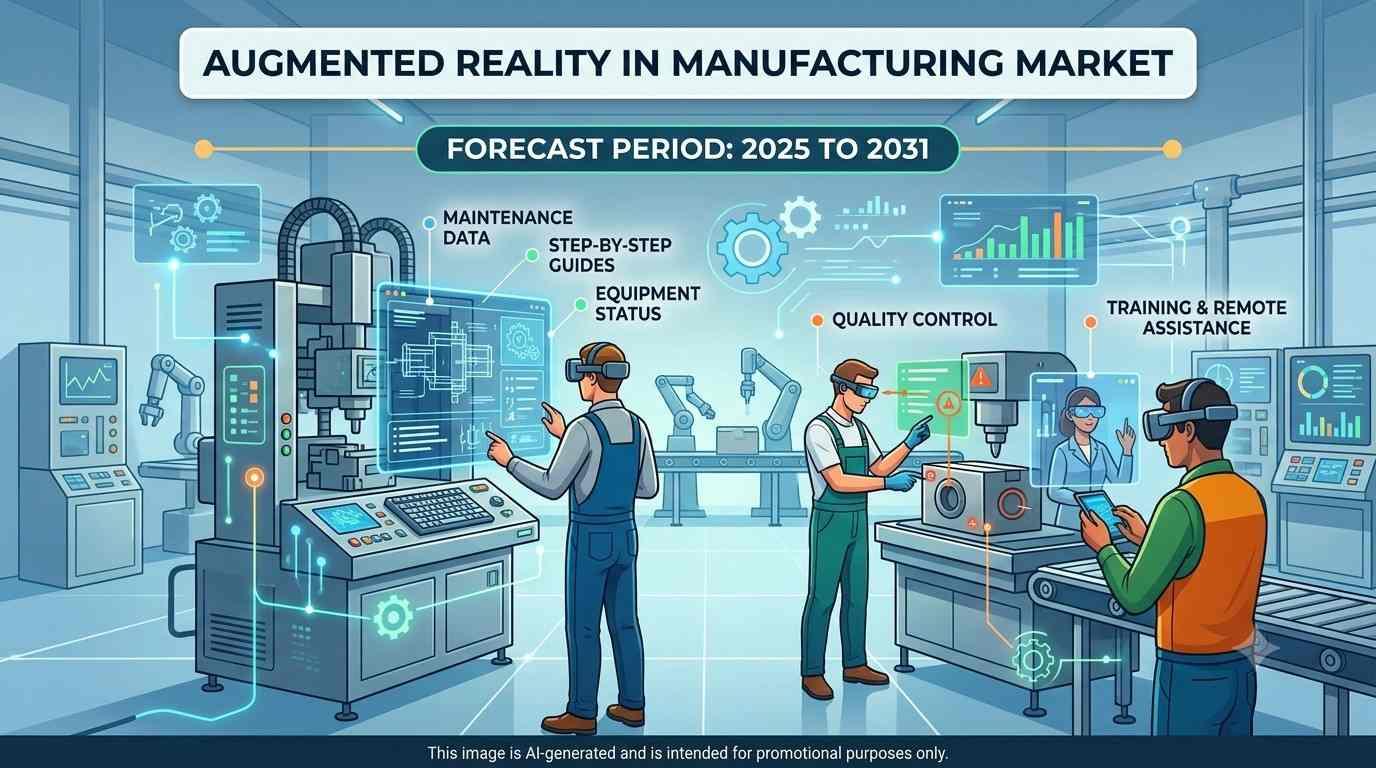
The Augmented Reality in Manufacturing Market is expanding as industrial OEMs, discrete manufacturers, enterprise software providers, and system integrators shift toward digital workflows that reduce error rates, accelerate assembly time, and enhance worker efficiency. Growth is supported by Industry 4.0 adoption, digital twin integration, cloud-based AR platforms, and investments in smart factory infrastructure.
The Augmented Reality In Manufacturing Market size is expected to reach US$ 78.06 Billion by 2031. The market is anticipated to register a CAGR of 29.2% during 2025-2031.
What is driving the market?
Workforce skill gaps, remote technical assistance, and operational efficiency demands are the principal growth drivers. Industrial operators are increasingly required to streamline complex assembly tasks, minimize unscheduled downtime, enforce safety compliance, and address retiring skilled labor. Automotive, aerospace, heavy machinery, and electronics manufacturers are seeking AR solutions that overlay real-time spatial data and guided instructions onto physical production lines without impairing ergonomics or worker safety.
The transition is moving beyond pilot phase demonstrations toward enterprise-wide industrial deployment. Solution providers are investing in hands-free smart glasses, spatial computing platforms, AI-assisted computer vision, and systems designed to integrate directly with PLM (Product Lifecycle Management) and ERP architectures. High hardware deployment costs, field-of-view battery constraints, enterprise cyber-security concerns, and legacy IT integration remain important constraints.
Which region leads?
North America leads the market, accounting for an estimated 32%–36% share in 2025, supported by high smart factory maturity, early technology adoption, and significant R&D spending by aerospace and automotive manufacturers.
Asia Pacific is the fastest-growing region with a projected CAGR of 21.5%–23.5%. Growth is supported by rapid industrial automation, government-backed smart manufacturing initiatives, electronics manufacturing density, and expanding industrial IoT infrastructure. China, Japan, South Korea, and India present significant opportunities as expanding production volumes coincide with investments in industrial digitisation. Europe holds an estimated 26%–30% share, driven by industrial digitalization strategies, automotive engineering adoption, and strict workplace safety guidelines.
Which segment leads?
Head-Mounted Displays (HMDs) & Smart Glasses is the leading device segment, representing an estimated 55%–59% of market revenue in 2025. Its position is supported by the necessity for hands-free operation on assembly floors, ergonomic advancements, improved battery life, and spatial mapping capabilities. Software platforms and cloud AR services represent the fastest-growing component segment as subscription-based enterprise SaaS models gain traction.
By application, Assembly & Maintenance leads with an estimated 38%–42% share in 2025, reflecting high adoption for real-time step-by-step guidance, component tracking, and remote expert support. Training & Simulation is identified as a high-growth application segment, with an estimated 22.0%–24.0% CAGR, as immersive onboarding environments reduce training duration and error rates for complex industrial tasks.
Which companies are prominent?
The report identifies PTC Inc. (Vuforia), Microsoft Corporation, Siemens AG, Dassault Systèmes, TeamViewer AG (Frontline), Vuzix Corporation, Augmentir Inc., Magic Leap, Google LLC, and Apple Inc. as prominent market participants.
These companies compete across AR hardware, spatial enterprise software, industrial IoT integration, remote collaboration tools, and computer vision innovation. Strategic differentiation increasingly depends on computer vision accuracy, low-latency rendering, cloud interoperability, security protocols, and the ability to scale spatial content creation seamlessly across industrial sites. The list reflects the report's competitive landscape rather than a revenue-ranked market-share table.
What is changing in 2026?
The market is shifting from isolated AR proof-of-concept projects toward scalable, production-grade spatial workflows. System specifications increasingly require AI-driven object recognition, automatic digital twin synchronization, edge-computing infrastructure, and interoperability with factory MES (Manufacturing Execution Systems). Advanced industrial spatial standards and unified enterprise software protocols began applying broadly in 2026, creating unified benchmarks for spatial data security and hardware interoperability.
Manufacturers are accelerating adoption of generative AI-assisted AR guidance, lightweight industrial smart glasses, and ambient spatial computing interfaces. Technology procurement decisions are increasingly linked to measurable ROI—such as reduction in scrap rates, first-time fix improvements, and shorter mean-time-to-repair (MTTR)—creating demand for detailed analytics, validation testing, and deep collaboration between software vendors, hardware OEMs, and industrial end-users.
What are the major investment opportunities?
The strongest opportunities lie in industrial spatial software, enterprise AR platforms, AI-enabled computer vision, and ruggedized industrial wearables. Investment in lightweight optical engines, extended battery performance, edge computing devices, and low-latency connectivity can resolve existing hardware bottlenecks in factory environments. Long-term software contracts and deep system-integration partnerships can help tech vendors establish sticky recurring revenue models.
Additional opportunities include AR-guided quality control and inspection tools, automated CAD-to-AR conversion pipelines, spatial digital twin synchronization, and remote assistance solutions for global field services. Managed spatial computing platforms and AR hardware-as-a-service (HaaS) models may create sustainable recurring revenue where hardware updates, device management, and software support are delivered as an integrated package.
Asia Pacific offers attractive expansion potential through rapid factory modernization and high electronics and automotive production density. Investors should prioritize solutions that balance high visual fidelity, low latency, robust data security, and seamless integration with existing industrial IT frameworks.
The Insight Partners provides comprehensive syndicated and tailored market research services in the healthcare, technology, and industrial domains. Renowned for delivering strategic intelligence and practical insights, the firm empowers businesses to remain competitive in ever-evolving global markets.
• Email: sales@theinsightpartners.com
• Website: theinsightpartners.com
• Phone: +1-646-491-9876

 English
 Arabic
 French
 Spanish
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek