Healthcare Mobility Solutions Market Opportunities, Trends & Growth Forecast 2031
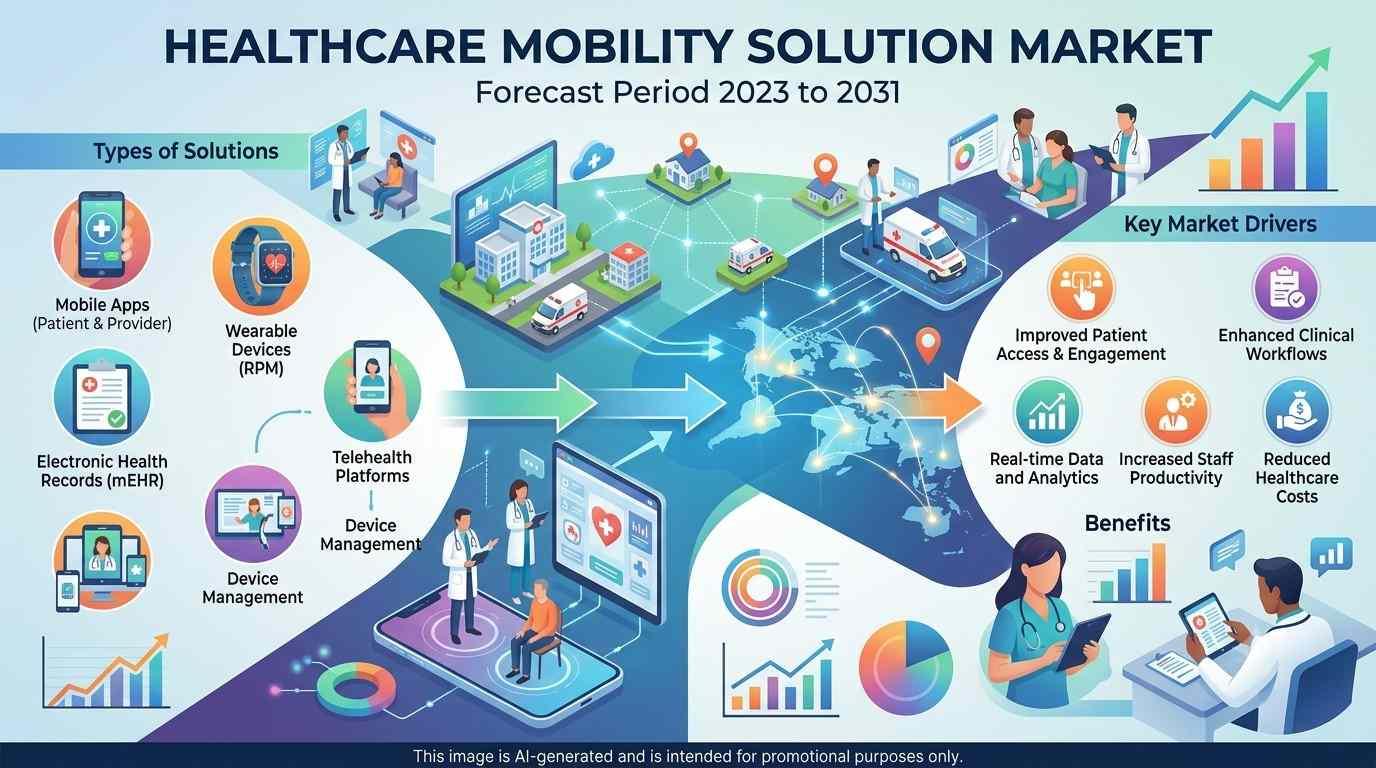
The Healthcare Mobility Solutions Market is expanding as healthcare providers, hospital networks, health insurance payers, and patients adopt mobile technologies to streamline clinical workflows, enable remote care, and improve patient outcomes. Growth is supported by digital transformation initiatives, widespread smartphone and tablet deployment in hospitals, expanding mHealth app usage, and investments in cloud and IoT infrastructure.
The Healthcare Mobility Solution Market was valued at US$ 118.2 billion in 2021 and is expected to reach US$ 362.2 billion by 2031. The market is expected to register a CAGR of 27.5% from 2023–2031.
What is driving the market?
Increasing chronic disease prevalence, growing demand for remote patient monitoring (RPM), and the clinical push for operational efficiency are the principal growth drivers. Healthcare providers are under continuous pressure to lower hospital readmission rates, optimize workforce scheduling, and eliminate manual documentation errors. Mobile point-of-care devices, patient tracking systems, and secure communication tools enable clinicians to access electronic health records (EHR) seamlessly in real time.
The transition is moving beyond basic device deployment toward unified digital health ecosystems. Suppliers are investing in AI-driven mobile health platforms, secure cloud storage, HIPAA-compliant messaging systems, and mobile apps that interface directly with wearable diagnostic tools. Data security risks, regulatory compliance overhead, and the cost of integrating mobile platforms with legacy hospital information systems (HIS) remain important constraints.
Which region leads?
North America leads the market, accounting for an estimated 42%–45% share in 2025, supported by advanced healthcare IT infrastructure, high smartphone penetration among clinicians, strong regulatory support, and major digital health investments.
Asia Pacific is the fastest-growing region with a projected CAGR of 10.5%–11.5%. Growth is propelled by expanding digital infrastructure, rising healthcare expenditures, government e-health initiatives, and rapidly growing smartphone adoption. China and India present significant opportunities as rising demand for accessible care coincides with hospital modernizations and tele-health expansion. Europe holds an estimated 26%–29% share, driven by digital healthcare mandates, regulatory frameworks supporting prescription apps, and expanding mHealth integration.
Which segment leads?
By Product & Service, Mobile Devices (Smartphones, Medical Tablets, Barcode Scanners) is the leading segment, representing an estimated 40%–43% of market revenue in 2025. Its position is supported by widespread adoption at bedside care, point-of-care administration, and medical asset tracking. mHealth & Mobile Applications is identified as the fastest-growing segment, expanding at a CAGR above 12%, driven by remote patient monitoring, chronic disease management apps, and patient-portal engagement.
By End User, Healthcare Providers (Hospitals & Clinics) leads with an estimated 52%–56% share in 2025, reflecting continuous procurement of enterprise mobility platforms for nurses, doctors, and operational staff.
Which companies are prominent?
The report identifies Oracle (Cerner), Zebra Technologies Corporation, Koninklijke Philips N.V., GE HealthCare, Apple Inc., Cisco Systems, McKesson Corporation, AirStrip Technologies, Omron Healthcare, and Microsoft Corporation as prominent market participants.
These companies compete across enterprise mobility software, medical-grade mobile devices, wireless network infrastructure, telehealth platforms, and cloud solutions. Strategic differentiation increasingly depends on data security/encryption capabilities, EHR interoperability, user interface simplicity, and AI integration for predictive patient alerts. The list reflects the report's competitive landscape rather than a revenue-ranked market-share table.
What is changing in 2026?
The market is shifting from isolated mobile app adoption toward fully integrated, compliance-ready healthcare enterprise platforms. Procurement decisions now prioritize real-time clinical data synchronization, end-to-end zero-trust cybersecurity, and seamless integration with hospital IoT systems. Additionally, regulatory frameworks like the EU's European Health Data Space (EHDS) rules and updated FDA digital health guidance are setting stricter baselines for data mobility and cross-platform interoperability.
Solution providers are accelerating ambient AI documentation tools, mobile-first clinician workflows, and advanced remote patient monitoring suites. Healthcare buying groups are demanding verified clinical outcomes and data interoperability rather than standalone mobility features, prompting strategic alliances between software vendors, medical device manufacturers, and cloud platforms.
What are the major investment opportunities?
The strongest opportunities lie in AI-powered clinical mobility platforms, integrated remote patient monitoring (RPM) hardware, secure health data exchanges, and specialized mHealth applications. Investment in robust cloud infrastructure, clinical communication systems, and cyber-resilient point-of-care devices can improve operational efficiency and patient satisfaction.
Additional opportunities include mobile solutions tailored for home healthcare services, automated asset tracking (RTLS) within hospital facilities, and personalized chronic disease management tools.
Asia Pacific offers attractive expansion potential due to vast underserved populations, rising smartphone adoption, and aggressive government health IT digitalization drives. Investors should prioritize vendors delivering strong interoperability, strict data privacy compliance, clear ROI for health systems, and seamless integration into existing electronic health record environments.
The Insight Partners provides comprehensive syndicated and tailored market research services in the healthcare, technology, and industrial domains. Renowned for delivering strategic intelligence and practical insights, the firm empowers businesses to remain competitive in ever-evolving global markets.
• Email: sales@theinsightpartners.com
• Website: theinsightpartners.com
• Phone: +1-646-491-9876

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek