


Canned Tuna Market Evolves from Pantry Staple to Sustainability-Driven Protein Category of USD 20.6 Billion Industry
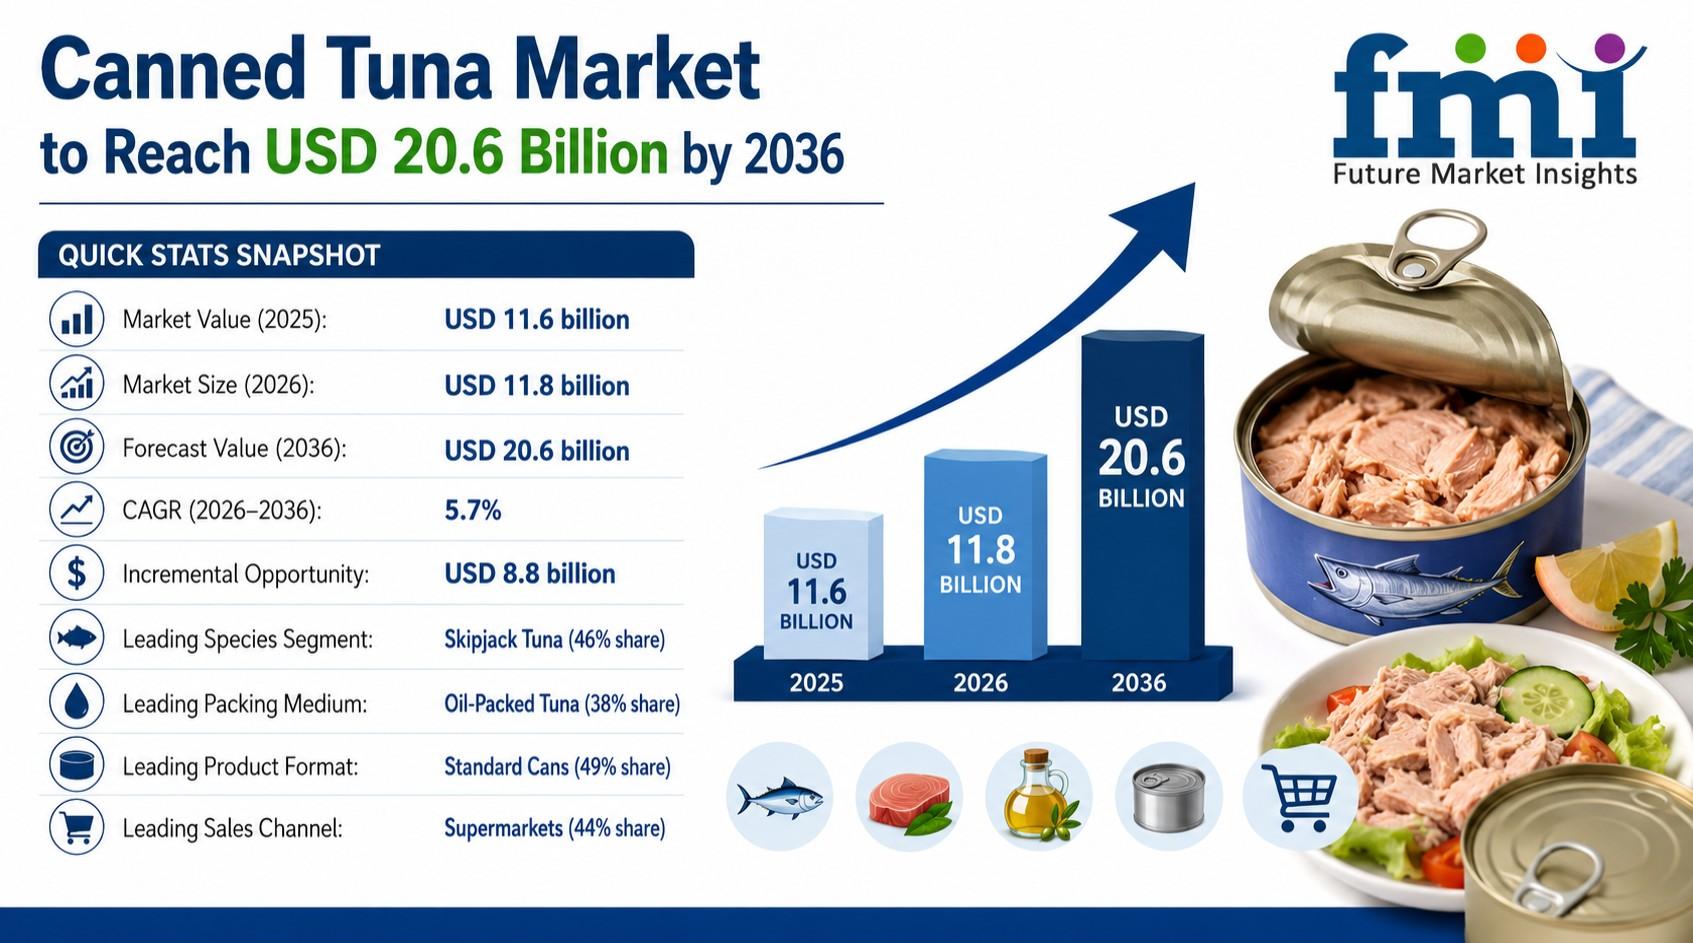
The global canned tuna market is transitioning from a traditional shelf-stable seafood category into a strategically important segment within affordable protein consumption, retail convenience, and sustainability-led packaged food systems. As consumers increasingly prioritize long shelf life, accessible nutrition, and meal convenience, canned tuna is expanding beyond emergency pantry usage into a mainstream everyday protein solution across households, institutional buyers, and foodservice channels. At the same time, sourcing transparency, responsible fishing programs, private-label expansion, and ready-to-eat product innovation are redefining competitive positioning across major seafood markets, according to latest insights by future market insights.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
https://www.futuremarketinsights.com/reports/sample/rep-gb-14896
Quick Stats Snapshot
• Market Value (2025): USD 11.6 billion
• Market Size (2026): USD 11.8 billion
• Forecast Value (2036): USD 20.6 billion
• CAGR (2026–2036): 5.7%
• Incremental Opportunity: USD 8.8 billion
• Leading Species Segment: Skipjack Tuna (46% share)
• Leading Packing Medium: Oil-Packed Tuna (38% share)
• Leading Product Format: Standard Cans (49% share)
• Leading Sales Channel: Supermarkets (44% share)
• Fastest-Growing Markets: Thailand (5.4% CAGR) and Indonesia (5.2% CAGR)
• Key Growth Regions: Asia-Pacific, Europe, and North America
Market Size and Forecast: Shelf-Stable Protein Demand Reinforces Long-Term Industry Growth
The canned tuna market is projected to expand from USD 11.8 billion in 2026 to USD 20.6 billion by 2036, registering a CAGR of 5.7% during the forecast period. Unlike many fresh seafood categories exposed to cold-chain volatility and shorter shelf life, canned tuna continues benefiting from stable retail demand, broad affordability, and strong integration into household meal planning.
The category has evolved from a basic preserved seafood product into a versatile protein format spanning standard cans, flavored offerings, tuna salads, ready meals, and premium olive-oil-based products. Retailers increasingly view canned tuna as a resilient high-turnover category capable of supporting both branded and private-label shelf strategies across supermarkets, club stores, convenience outlets, and digital grocery platforms.
At the same time, producers are balancing large-scale volume economics with rising expectations around sustainability, sourcing transparency, labor practices, and product diversification. This shift is gradually moving the industry beyond commodity-driven competition toward value-added differentiation built around traceability, convenience, and premium shelf positioning.
As inflation-sensitive consumers continue prioritizing affordable proteins and retailers strengthen shelf-stable food assortments, canned tuna remains positioned as one of the most resilient segments within the global packaged seafood industry.
Key Growth Drivers: Convenience, Retail Expansion, and Sustainability-Led Sourcing
1. Rising Demand for Shelf-Stable Protein Products
Consumers continue prioritizing food formats that combine affordability, convenience, and extended storage life. Canned tuna benefits from repeat household usage because it requires no refrigeration prior to opening and integrates easily into quick meals, salads, sandwiches, and ready-to-eat recipes.
2. Expansion of Supermarket and Private-Label Programs
Large retailers are expanding canned seafood shelf space through both branded and private-label assortments. Supermarkets favor canned tuna because of its steady turnover, lower spoilage risk, and compatibility with value-driven grocery purchasing patterns.
3. Product Innovation in Ready-to-Eat and Flavored Formats
Manufacturers are increasingly diversifying portfolios with flavored tuna, snack kits, ready-to-eat meals, tuna salads, and convenience-focused packaging systems targeting younger consumers and urban retail channels.
4. Sustainability and Responsible Fishing Programs
Responsible sourcing initiatives are becoming increasingly important across global seafood procurement systems. Brands are strengthening sustainability disclosures and fishery traceability programs to maintain retailer confidence and reduce reputational risk.
5. Growth in Export-Oriented Seafood Processing
Countries such as Thailand and Indonesia continue scaling export-focused processing infrastructure, enabling stronger global supply integration and improved cost competitiveness across canned tuna production systems.
Market Challenges: Input Cost Volatility and Sourcing Concentration Risks
Despite relatively stable long-term demand, the canned tuna market continues to face several
operational and commercial pressures:
• Rising aluminum and metal packaging costs
• Volatility in edible oil pricing affecting premium tuna lines
• Quota-linked tuna sourcing constraints
• Labor and fishery compliance scrutiny across export hubs
• Margin pressure within private-label retail contracts
• Increasing competition from alternative protein snacks and seafood formats
Sourcing concentration remains one of the industry's most important structural risks. A large share of global supply continues to move through a limited number of export-processing hubs, increasing exposure to freight disruptions, fishery regulation changes, and geopolitical trade dynamics.
Processors must increasingly balance cost efficiency with sustainability compliance, retailer transparency requirements, and long-term sourcing resilience.
Emerging Opportunities: Premiumization, Convenience Innovation, and Traceable Seafood Systems
Several emerging opportunities are expected to influence future market positioning:
• Premium olive-oil and gourmet canned tuna lines
• Sustainability-certified and traceable seafood products
• Ready-to-eat tuna meals and snack kits
• Protein-focused convenience foods for younger consumers
• Digital retail and direct-to-consumer seafood distribution
• Product diversification using tuna-derived nutrition ingredients
Companies capable of integrating responsible sourcing, retail-ready convenience, and premium flavor positioning are expected to strengthen shelf presence and pricing power across developed packaged food markets.
Segmentation Insights: Skipjack and Supermarkets Continue to Anchor Industry Demand
By Species
Skipjack tuna is projected to account for 46% of the species segment in 2026 due to its strong raw material availability, mild flavor profile, and cost efficiency across large-scale retail programs. Its commercial flexibility supports both branded and private-label formats globally.
By Packing Medium
Oil-packed tuna is expected to represent 38% of the packing medium segment in 2026, supported by strong demand across Mediterranean and premium retail markets where olive-oil formulations remain closely associated with product quality and flavor retention.
By Product Format
Standard cans are projected to account for 49% of the product format segment because they continue to fulfill the largest household and institutional demand requirements across mainstream retail systems.
By Sales Channel
Supermarkets are expected to hold 44% of sales channel share in 2026 as repeat household replenishment and high product visibility continue supporting strong shelf turnover.
By Price Positioning
Mass-market canned tuna remains the leading price positioning segment as affordability continues to shape consumer purchasing behavior across both developed and emerging retail markets.
By End Use
Retail consumption is projected to account for 68% of end-use demand due to the category’s strong integration into everyday household meal planning and pantry stocking behavior.
Regional Analysis: Asia-Pacific Strengthens Processing Leadership While Europe Maintains Premium Retail Positioning
High-Growth Markets
• Thailand (5.4% CAGR): Export-oriented seafood processing scale and global sourcing integration continue supporting market leadership.
• Indonesia (5.2% CAGR): Tuna exports and improved tariff access for processed seafood strengthen long-term production economics.
• Spain (5.0% CAGR): Strong canning infrastructure and re-export positioning support continued expansion across European seafood markets.
Mature Markets
• United States (4.8% CAGR): Stable growth supported by widespread household adoption, private-label penetration, and protein-focused grocery demand.
• Italy (4.6% CAGR): Deep household integration and premium olive-oil product positioning continue supporting retail resilience.
• South Korea (4.2% CAGR): Convenience-led consumption and supermarket penetration maintain stable growth dynamics.
• Japan (4.0% CAGR): Mature seafood consumption habits contribute to slower but steady canned tuna demand.
Regional market dynamics increasingly reflect different strategic priorities:
• Asia-Pacific emphasizes export manufacturing and sourcing scale
• Europe focuses on premiumization and sustainability-led retail positioning
• North America prioritizes convenience, value packs, and private-label expansion
• Developed seafood economies emphasize traceability and responsible sourcing systems
Competitive Landscape: Sustainability, Retail Access, and Sourcing Scale Define Market Leadership
The canned tuna industry remains moderately concentrated, with a relatively small group of multinational seafood processors controlling significant branded and private-label production capacity.
Leading companies including Thai Union Group, Bolton Food, Dongwon Industries, StarKist Co., and Bumble Bee Seafoods are strengthening investments in sustainability programs, sourcing traceability, retail partnerships, and convenience-oriented product innovation.
Recent industry developments suggest competitive differentiation is increasingly influenced by:
• Responsible fishing and sustainability certifications
• Stable tuna sourcing and processing integration
• Retail shelf positioning and promotional flexibility
• Product innovation in snack kits and ready meals
• Ability to support branded and private-label portfolios simultaneously
In 2025, Thai Union secured a USD 150 million Blue Loan to strengthen sustainable seafood sourcing initiatives and supply chain practices. Meanwhile, Bolton reported that 99.7% of tuna used in branded products during 2024 came from responsible fishing practices, reinforcing sustainability-led positioning across retail markets.
Strategic Implications for Industry Stakeholders
• Retailers should prioritize seafood suppliers capable of supporting consistent fill rates and sustainability documentation
• Investors may increasingly focus on processors with diversified sourcing and premium product capabilities
• Packaged food companies should expand convenience-oriented tuna formats aligned with quick-meal consumption trends
• Seafood processors need stronger traceability systems and labor-compliance frameworks to maintain export competitiveness
• Strategy teams must evaluate sourcing concentration risks linked to global tuna processing hubs
Full Report for Detailed Insights: https://www.futuremarketinsights.com/reports/canned-tuna-market
Future Outlook: From Commodity Seafood to Strategic Convenience Protein Platform
Over the next decade, canned tuna is expected to evolve beyond its historical identity as a low-cost pantry staple into a broader convenience-focused and sustainability-sensitive protein category. Consumer demand for affordable shelf-stable nutrition is likely to remain resilient even as retail systems become increasingly focused on traceability, premiumization, and responsible sourcing.
The category’s long-term growth trajectory will not depend solely on higher tuna volumes, but on the ability of processors and brands to balance sourcing transparency, retail convenience, flavor innovation, and cost efficiency within increasingly competitive packaged food environments.
As sustainability programs become more visible within global grocery systems and consumers continue prioritizing convenient protein options, canned tuna is expected to maintain its position as one of the most commercially resilient segments within the global seafood industry.
Executive Takeaways
• The canned tuna market is projected to reach USD 20.6 billion by 2036
• Growth is being driven by shelf-stable protein demand and retail convenience trends
• Skipjack tuna remains the dominant species segment with 46% share
• Supermarkets continue leading sales channel demand with 44% market share
• Oil-packed tuna maintains strong premium retail positioning across Mediterranean markets
• Thailand and Indonesia are emerging as the fastest-growing processing and export hubs
• Sustainability programs and responsible fishing practices are becoming key competitive differentiators
• Product innovation in ready-to-eat meals and snack kits is reshaping category positioning
• Canned tuna is evolving from a commodity pantry product into a strategically differentiated packaged protein category
Explore More Related Studies Published by FMI Research
Deli Meat Market : https://www.futuremarketinsights.com/reports/deli-meat-market
Decaffeinated Coffee Market : https://www.futuremarketinsights.com/reports/decaffeinated-coffee-market
Seitan Market : https://www.futuremarketinsights.com/reports/seitan-market
About Future Market Insights (FMI)
Future Market Insights, Inc. is an ESOMAR-certified, ISO 9001:2015 market research and consulting organization trusted by Fortune 500 companies. With a global presence across the U.S., UK, India, and Dubai, FMI delivers data-driven insights across 30+ industries and 1200 markets worldwide.
Contact Us
Future Market Insights Inc.
Christiana Corporate, 200 Continental Drive,
Suite 401, Newark, Delaware – 19713, USA
T: +1-347-918-3531
For Sales Enquiries: sales@futuremarketinsights.com
Website: https://www.futuremarketinsights.com

 English
 Arabic
 French
 Spanish
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek