


8K Technology Market: Growth Outlook, Emerging Trends & Opportunities Through 2031
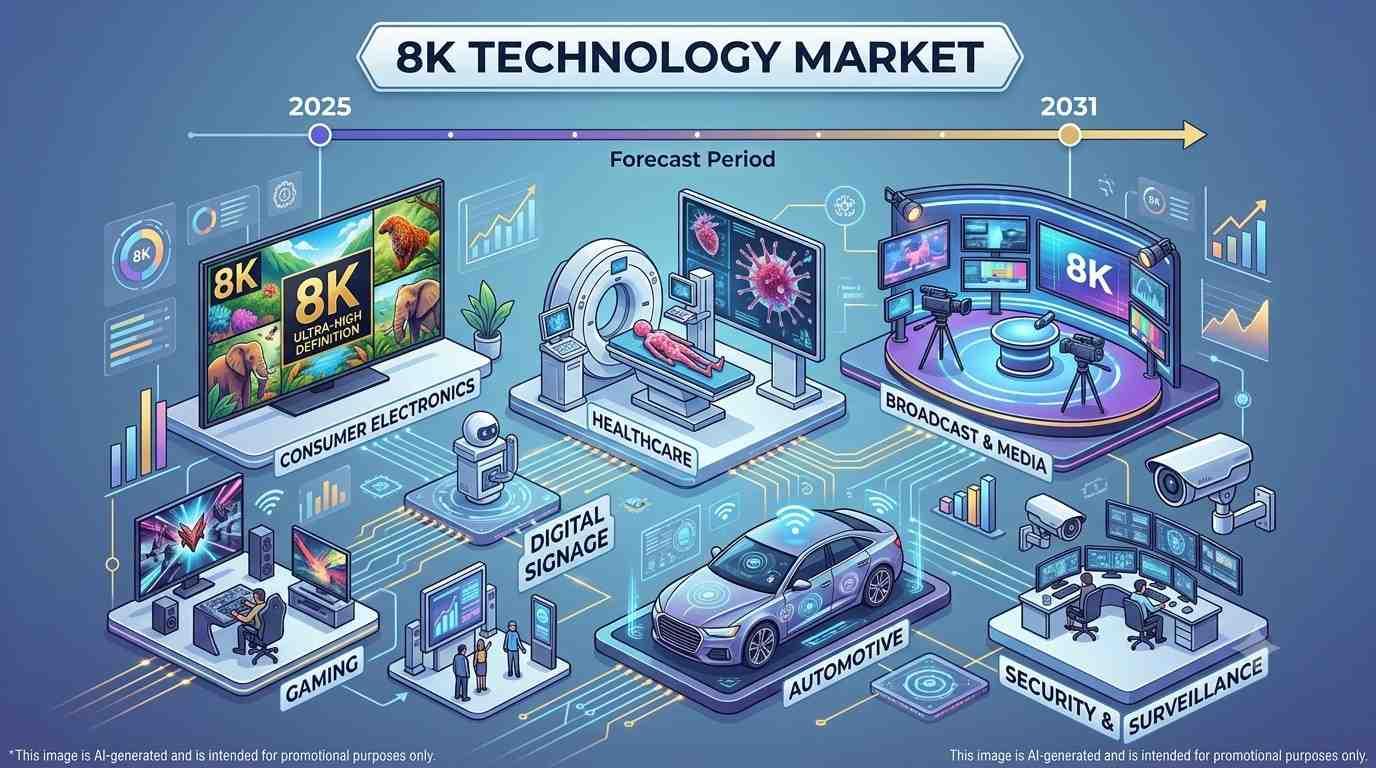
The 8K Technology Market is expanding as display manufacturers, content creators, broadcasters, and healthcare providers transition toward ultra-high-definition visual ecosystems that deliver unmatched image clarity, detail, and immersive viewing experiences. Growth is supported by advancements in panel manufacturing, AI-powered image processing, next-generation gaming, high-bandwidth streaming infrastructure, and rising professional applications.
The 8K Technology Market size is expected to reach US$ 52.33 Billion by 2031. The market is anticipated to register a CAGR of 29.6% during 2025–2031.
What is driving the market?
Surging consumer demand for large-screen home entertainment, advancements in display panel technologies (OLED, Micro-LED, Mini-LED), and the integration of AI-driven upscaling are the principal growth drivers. Display producers are increasingly deploying AI-based upscaling algorithms to enhance 1080p and 4K content to near-8K quality, overcoming immediate native content limitations. Consumer electronics manufacturers, sports broadcasters, gaming studios, and medical imaging providers are seeking ultra-high resolution ($7680 \times 4320$ pixels) to enhance visual precision, immersive detail, and diagnostic accuracy.
The transition is moving beyond premium consumer televisions toward comprehensive ecosystem adoption. Suppliers are investing in 8K-capable cameras, professional monitors, processing chips, and advanced compression standards (such as VVC/H.266) to streamline bandwidth consumption. High infrastructure costs, limited native 8K streaming content, and bandwidth constraints in developing regions remain important constraints.
Which region leads?
Asia Pacific leads the market, accounting for an estimated 36%–38% share in 2025, and is also the fastest-growing region with a projected CAGR exceeding 42%. Growth is supported by heavy display panel manufacturing capacity, rapid consumer electronics adoption, expanding 5G network coverage, and strong government backing for ultra-HD broadcasting. China, Japan, and South Korea present significant opportunities due to the presence of major display OEMs, early consumer adoption, and robust investments in 8K broadcasting infrastructure.
North America holds an estimated 28%–32% share, supported by high consumer spending on premium home entertainment, strong demand for next-generation gaming consoles, and early adoption in medical imaging and digital cinematography. Europe accounts for approximately 22%–26%, with demand driven by commercial visualization, professional media production, sports broadcasting, and industrial applications.
Which segment leads?
Televisions is the leading product segment, representing an estimated 42%–46% of market revenue in 2025. Its position is supported by declining panel production costs, consumer preference for screen sizes of 65 inches and above, and aggressive marketing by tier-1 TV brands. The segment is forecast to maintain strong double-digit growth through 2033.
By end-use industry, Consumer Electronics leads with an estimated 50%–55% share in 2025, reflecting high volume adoption across home theater systems, gaming monitors, and personal devices. Healthcare & Medical Imaging is identified as a high-growth end-use segment, driven by the adoption of 8K surgical monitors and diagnostic imaging systems that demand granular physical detail for complex procedures and surgical training.
Which companies are prominent?
The industry features major technology and display leaders, including Samsung Electronics, LG Electronics, Sony Group Corporation, Sharp Corporation, Panasonic Corporation, Canon Inc., Dell Technologies, TCL Technology, Hisense, and BOE Technology Group.
These companies compete across display panel fabrication, consumer electronics, professional camera manufacturing, image processing processors, and commercial visualization. Strategic differentiation increasingly depends on proprietary AI upscaling chipsets, panel brightness and efficiency improvements, HDR technology integration, and price-competitiveness at commercial scale. The list reflects the sector's key market participants rather than a revenue-ranked market-share table.
What is changing in 2026?
The market is shifting from early-adopter luxury positioning toward mainstream hardware integration and functional AI software solutions. Product specifications increasingly emphasize neural processing units (NPUs) built directly into display hardware to handle real-time frame interpolation, noise reduction, and AI upscaling. On the regulatory side, revised energy efficiency metrics—such as the European Union's updated Energy Efficiency Index (EEI) standards—are forcing display manufacturers to innovate low-power panel designs and eco-friendly backlight technologies without compromising luminance.
Manufacturers are accelerating micro-LED development, high-refresh-rate 8K gaming panels, and advanced camera gear for live sports streaming. Procurement decisions in broadcasting and commercial sectors are increasingly linked to end-to-end compatibility—from capture and encoding to transmission and display—creating demand for cross-industry standardization and partnerships between hardware makers, cloud streaming platforms, and telecom operators.
What are the major investment opportunities?
The strongest opportunities lie in AI-powered video processing chips, micro-LED display manufacturing, cloud-based 8K video compression solutions, and specialized medical imaging hardware. Investment in high-efficiency codecs (such as VVC and AV1), edge computing nodes, and high-capacity content distribution networks (CDNs) can resolve bandwidth bottlenecks and lower streaming costs for end-users.
Additional opportunities include 8K professional production gear (cameras, lenses, monitors), high-end gaming monitors, enterprise simulation/VR hardware, and digital signage for transport and retail hubs. Hardware-as-a-Service (HaaS) models in healthcare, live events, and commercial broadcasting may create recurring revenue where high upfront equipment costs are spread across operational service contracts.
Asia Pacific offers attractive expansion potential through established supply chains, high-density consumer electronics markets, and rapid infrastructure buildout. Investors should prioritize technology providers that combine energy-efficient display architectures, robust AI upscaling capabilities, and cost-effective scaling for mass-market adoption.
The Insight Partners provides comprehensive syndicated and tailored market research services in the healthcare, technology, and industrial domains. Renowned for delivering strategic intelligence and practical insights, the firm empowers businesses to remain competitive in ever-evolving global markets.
• Email: sales@theinsightpartners.com
• Website: theinsightpartners.com
• Phone: +1-646-491-9876

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek