


Liquid Waste Management Market Size, Share, Demand & Growth Report 2026–2034
Liquid Waste Management Market Overview
The global Liquid Waste Management Market comprises services, equipment, and treatment systems used for the collection, transportation, treatment, processing, disposal, recycling, and reuse of wastewater and other liquid waste streams. The market covers municipal wastewater, industrial wastewater, commercial wastewater, agricultural liquid waste, and other liquid waste generated by households, businesses, institutions, and industrial facilities.
Liquid waste management is supported by mandatory wastewater treatment requirements, aging sewer networks, population growth, industrial discharge controls, water scarcity, and increasing demand for treated wastewater. UN-Water reports that among 107 countries providing wastewater data for 2022, 76% of total wastewater received some treatment, while only 60% was safely treated among the smaller group of countries with sufficient data for that indicator.
The market is gradually shifting from a disposal-focused model toward integrated treatment, resource recovery, and water reuse. Treated wastewater is increasingly being considered as an alternative source of water for industrial processes, irrigation, cooling, municipal applications, and other non-potable uses.
Infrastructure investment is also supporting market expansion. Governments and utilities are investing in wastewater treatment plants, sewer extensions, pumping stations, advanced filtration, disinfection, monitoring systems, sludge management, and treatment-plant rehabilitation. Water scarcity and tighter environmental standards are further increasing demand for advanced treatment and reuse technologies.
Request Sample Link:
Liquid Waste Management Market Size
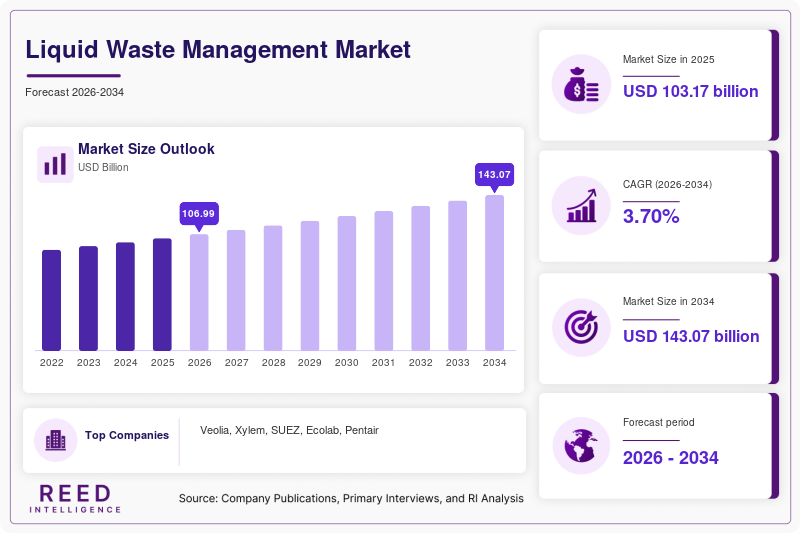
The global Liquid Waste Management Market size was valued at USD 103.17 billion in 2025 and is projected to grow from USD 106.99 billion in 2026 to USD 143.08 billion by 2034, registering a CAGR of 3.70% during 2026–2034. Mandatory wastewater treatment, infrastructure renewal, industrial discharge requirements, water scarcity, and increasing wastewater reuse are supporting market growth.
North America dominated the market with approximately 29% share in 2025, while APAC is expected to be the fastest-growing region at approximately 5.2% CAGR through 2034. Municipal Wastewater held the leading 55% market share in 2025, while Industrial Wastewater is projected to grow fastest at approximately 4.8% CAGR.
Biological Treatment represented approximately 46% of the market in 2025, while Advanced Treatment is projected to grow fastest at approximately 5.4% CAGR. Treatment & Processing accounted for approximately 42% of the Service segment, while Recycling & Reuse is projected to grow at approximately 6.1% CAGR. Municipal End Use represented approximately 50% of the market, while Industrial End Use is projected to grow fastest at approximately 5.0% CAGR.
Liquid Waste Management Market Trends
Shift Toward Water Reuse and Resource Recovery
The liquid waste management industry is increasingly moving beyond conventional wastewater disposal toward water reuse and resource recovery. Utilities and industrial users are evaluating treated wastewater as an alternative source for irrigation, industrial processing, cooling, municipal cleaning, and other non-potable applications.
Water reuse requires higher levels of treatment and monitoring, increasing demand for tertiary treatment, membrane filtration, ultraviolet disinfection, reverse osmosis, activated carbon, and advanced water-quality monitoring systems.
Wastewater treatment plants are also being developed as resource-recovery facilities. Biogas, nutrients, treated water, and other recoverable resources can create additional value from wastewater and sludge while reducing dependence on external resources.
Advanced Treatment and Digital Water Management
Increasing environmental requirements are encouraging utilities and industrial facilities to adopt advanced treatment technologies. Membrane systems, advanced oxidation, adsorption, ultraviolet treatment, nutrient removal, and high-efficiency filtration are gaining importance for removing complex pollutants and producing higher-quality treated water.
Digital monitoring is also becoming more important. Sensors, automated process controls, water-quality analytics, predictive maintenance, and remote monitoring allow treatment operators to improve plant efficiency and identify operational problems more quickly.
The combination of advanced treatment and digital systems is particularly relevant for industrial facilities and water-reuse projects where consistent water quality and operational reliability are important.
Liquid Waste Management Market Drivers
Increasing Wastewater Treatment Requirements and Infrastructure Renewal
Wastewater treatment remains an essential requirement for municipalities and industrial facilities, creating recurring demand for collection systems, pumping stations, biological treatment, filtration, disinfection, sludge handling, monitoring equipment, and treatment-plant rehabilitation.
Aging sewer networks and treatment infrastructure are increasing the need for modernization. Population growth and urbanization are also placing additional pressure on existing collection and treatment systems, particularly in rapidly developing cities.
Government financing further supports infrastructure investment. In the U.S., EPA's Clean Water State Revolving Fund provides financing for wastewater infrastructure, including treatment-plant upgrades, sewer extensions, disinfection systems, and collection-system rehabilitation. India's AMRUT 2.0 also supports sewerage, septage management, treatment-plant expansion, and infrastructure rehabilitation.
Water Scarcity Is Turning Wastewater Into a Usable Resource
Water scarcity is increasing the economic value of treated wastewater. Instead of treating effluent only to meet discharge standards, utilities and industrial users are increasingly evaluating wastewater as a source of process water, irrigation water, cooling water, and other non-potable supplies.
EPA's WRAP 2.0 emphasizes water reuse for industrial, technology, and energy applications. Similar initiatives are being developed internationally, including treated-sewage reuse for landscaping, agriculture, and industrial applications.
This trend is increasing demand for tertiary treatment, membranes, ultraviolet disinfection, reverse osmosis, monitoring, and water-distribution infrastructure. The commercial potential is particularly strong in water-stressed regions and industrial areas with high freshwater requirements.
Industrial Contaminants and Tighter Environmental Controls
Industrial wastewater can contain more complex contaminant profiles than conventional municipal wastewater, creating demand for specialized treatment systems and monitoring technologies.
Emerging contaminants such as PFAS are increasing regulatory attention. The U.S. EPA has identified wastewater and sewage sludge as potential pathways for PFAS and has continued developing guidance related to PFOA and PFOS risks in biosolids.
The European Union's revised wastewater framework also places greater attention on pollutants, treatment performance, resource recovery, and environmental protection. These requirements support demand for advanced oxidation, adsorption, membrane treatment, biological processes, filtration, monitoring, and specialized sludge-management systems.
Liquid Waste Management Market Restraints
High Capital and Operating Costs
Liquid waste management requires substantial infrastructure, including sewer networks, pumping stations, treatment plants, sludge-handling systems, storage facilities, monitoring equipment, and advanced treatment technologies.
Energy consumption is another important operating expense. Aeration, pumping, membrane filtration, ultraviolet treatment, and reverse osmosis can require significant energy, particularly when high-quality treated water is required.
Advanced treatment for water reuse or emerging-contaminant removal can further increase capital and operating costs. These financial requirements can create barriers for smaller municipalities and price-sensitive industrial customers.
Fragmented Regulation and Uneven Infrastructure Capacity
Liquid waste management depends heavily on local discharge permits, environmental standards, sewerage infrastructure, water pricing, land availability, and municipal financing. Treatment requirements can therefore vary substantially between countries and jurisdictions.
UN-Water's assessments demonstrate significant differences in wastewater collection and safe treatment between regions and income groups. Developing markets may face limited treatment capacity, while mature markets may need extensive infrastructure rehabilitation and upgrades.
This uneven infrastructure environment increases project-development complexity and makes standardized technology deployment more difficult. Operators must adapt systems to local regulatory requirements, wastewater characteristics, financing structures, and available infrastructure.
Liquid Waste Management Market Opportunities
Water Reuse and Resource Recovery
Water reuse represents a major commercial opportunity as utilities and industries seek to reduce freshwater consumption. Treated wastewater can support irrigation, industrial processes, cooling, municipal cleaning, construction, and other non-potable applications.
Wastewater treatment plants can also recover biogas, nutrients, and other resources from wastewater and sludge. This creates an opportunity to transform treatment facilities from cost-focused infrastructure into resource-recovery facilities that generate additional economic value.
The European Union's revised wastewater framework promotes circularity through water reuse and resource recovery. Similar projects in France and other markets demonstrate how recycled water and energy recovery can be incorporated into long-term wastewater infrastructure planning.
Industrial Wastewater and High-Value Water Treatment
Industrial wastewater is creating opportunities for customized treatment systems because manufacturers increasingly require both environmental compliance and reliable water supplies.
Semiconductor, pharmaceutical, food and beverage, energy, mining, chemical, and data-center facilities can require high-quality process water and specialized wastewater treatment. These applications support demand for membrane systems, advanced biological treatment, digital monitoring, water-quality analytics, and outsourced treatment services.
Industrial water reuse can also reduce dependence on municipal freshwater supplies and support more closed-loop water systems. EPA's 2026 water-reuse strategy specifically identifies industry, technology, and energy as important areas for expanded water reuse.
Challenges in Liquid Waste Management Market
Complex Infrastructure, Treatment Requirements and Financing
Liquid waste management providers must balance treatment performance, regulatory compliance, energy consumption, infrastructure costs, water quality, environmental requirements, and customer affordability.
Municipal projects can require significant investment in sewer networks, pumping stations, treatment plants, and rehabilitation, while industrial facilities may require customized systems for complex contaminants and water-reuse applications.
The challenge is particularly significant in developing markets where wastewater generation is increasing faster than treatment capacity. Limited municipal financing, uneven infrastructure, technical-resource constraints, and different regulatory requirements can delay projects.
Operators and technology providers therefore need scalable treatment systems, efficient equipment, digital monitoring, flexible financing models, and integrated operation and maintenance services.
Top Players in Liquid Waste Management Market
- Veolia
- Xylem
- SUEZ
- Ecolab
- Pentair
- Kurita Water Industries
- Evoqua/Xylem
- Aquatech International
- DuPont Water Solutions
- Sulzer
- Alfa Laval
Liquid Waste Management Market Segments
By Waste Source
- Municipal Wastewater
- Industrial Wastewater
- Commercial Wastewater
- Agricultural & Other Liquid Waste
By Treatment Type
- Biological Treatment
- Physical Treatment
- Chemical Treatment
- Advanced Treatment
By Service
- Collection & Transportation
- Treatment & Processing
- Disposal
- Recycling & Reuse
By End Use
- Municipal
- Industrial
- Commercial
- Agriculture & Other End Uses
By Region
- North America
- Europe
- APAC
- Middle East and Africa
- LATAM
Conclusion
The global Liquid Waste Management Market is projected to grow from USD 106.99 billion in 2026 to USD 143.08 billion by 2034 at a CAGR of 3.70%. Increasing wastewater treatment requirements, aging infrastructure, industrial discharge controls, water scarcity, wastewater reuse, and resource recovery are supporting market expansion.
Municipal Wastewater currently leads the Waste Source segment with approximately 55% share, while Industrial Wastewater is projected to grow at approximately 4.8% CAGR. Biological Treatment accounts for approximately 46% of the Treatment Type segment, while Advanced Treatment is projected to grow at approximately 5.4% CAGR. Treatment & Processing leads the Service segment with approximately 42% share, while Recycling & Reuse is projected to grow at approximately 6.1% CAGR. Municipal End Use represents approximately 50% of the market, while Industrial End Use is projected to record the fastest growth at approximately 5.0% CAGR. North America remains the dominant regional market with approximately 29% share, while APAC is projected to record the fastest regional growth at approximately 5.2% CAGR through 2034.
Report Link:

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek