


Lung Cancer Surgery Market Size and Forecast Highlight Opportunities Through 2036
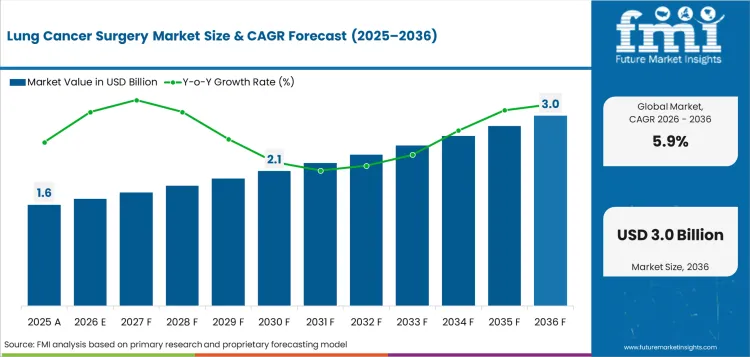
According to Future Market Insights (FMI), the global lung cancer surgery market is projected to grow from USD 1.6 billion in 2026 to USD 2.8 billion by 2036, expanding at a 5.9% CAGR during the forecast period. The market is expected to create an incremental opportunity of USD 1.2 billion between 2026 and 2036 as earlier-stage diagnosis, minimally invasive procedures, and robotic-assisted thoracic surgery support demand for surgical systems and instruments.
👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends:
https://www.futuremarketinsights.com/reports/sample/rep-gb-396
The market covers devices and systems used in curative thoracic surgery, including thoracoscopes, bronchoscopes, surgical staplers, robotic-assisted systems, and surgical energy instruments. Growing detection of operable lung cancer cases is increasing the number of patients entering multidisciplinary treatment discussions where surgery is considered.
Key Market Highlights
· Market Size (2026): USD 1.6 billion
· Forecast Value (2036): USD 2.8 billion
· CAGR (2026–2036): 5.9%
· Incremental Opportunity: USD 1.2 billion
· Leading Application: Lobectomy, with 42% share in 2026
· Leading End User: Hospitals, with 65% share in 2026
· Leading Product: Surgical staplers, with 31% share in 2026
· Leading Surgical Approach: Minimally invasive surgery, with 48% share in 2026
· Leading Cancer Type: Non-small cell lung cancer, with 80% share in 2026
· Fastest-Growing Country: India, at 7.1% CAGR through 2036
Global Segment Leaders
Lobectomy — 42% Share: Lobectomy is projected to remain the leading application in 2026 as full-lobe removal remains central to curative thoracic resections for eligible non-small cell lung cancer cases.
Hospitals — 65% Share: Hospitals account for the largest end-user share because complex thoracic procedures require specialist surgical teams, intensive care support, thoracic anesthesia, and multidisciplinary cancer boards.
Surgical Staplers — 31% Share: Surgical staplers represent the leading product category as pulmonary resections require controlled tissue division, vessel closure, and lung tissue sealing.
Minimally Invasive Surgery — 48% Share: Minimally invasive procedures lead the surgical approach segment as VATS adoption expands and hospitals seek approaches associated with reduced chest-wall trauma and recovery burden.
Non-Small Cell Lung Cancer — 80% Share: NSCLC represents the dominant cancer-type segment because most operable lung cancer cases fall within this category.
Country-Level Performance
· India – 7.1% CAGR (2026–2036): Private cancer hospital investment and expanding thoracic surgery capacity.
· China – 6.8% CAGR (2026–2036): Urban oncology infrastructure and wider minimally invasive surgery access.
· Brazil – 5.8% CAGR (2026–2036): Improving oncology referral networks in major cities.
· United States – 5.6% CAGR (2026–2036): Robotic surgery access and lung screening pathways.
· United Kingdom – 5.4% CAGR (2026–2036): Screening-driven identification of earlier-stage cases.
· Germany – 5.2% CAGR (2026–2036): Mature surgical infrastructure and disciplined device assessment.
· Japan – 4.9% CAGR (2026–2036): Aging population and increasing demand for lung-sparing procedures.
FMI projects India to record the fastest growth among the countries profiled, at 7.1% CAGR through 2036. Private cancer hospitals, particularly in major metropolitan centers, are expanding access to thoracic surgery teams and robotic platforms. China follows at 6.8%, supported by oncology infrastructure expansion across large urban hospital groups and greater access to minimally invasive procedures.
Brazil is forecast to expand at 5.8%, while the United States is projected at 5.6%. The U.S. market benefits from established thoracic surgery infrastructure, robotic systems, and lung screening pathways. The United Kingdom and Germany are expected to record CAGRs of 5.4% and 5.2%, respectively. Japan is projected at 4.9%, with an aging patient population supporting demand for procedures designed to preserve lung function.
👉 Access the Complete Report in PDF Format:
https://www.futuremarketinsights.com/reports/brochure/rep-gb-396
Market Drivers, Restraints and Opportunities
Earlier diagnosis is becoming a key factor affecting the surgical case pool. FMI notes that screening-driven stage shifts can bring more patients into treatment pathways before advanced disease limits curative surgical options. In England, the National Lung Cancer Audit reported that 40% of people diagnosed with lung cancer were diagnosed at stages 1 to 2 in 2024.
The adoption of video-assisted thoracoscopic surgery is also supporting demand for thoracoscopes and staplers. Robotic-assisted thoracic surgery is creating additional capital-equipment demand among hospitals with sufficient oncology case volumes.
Cost pressure remains a restraint, particularly for surgical staplers and energy systems. Hospitals increasingly compare reload prices with procedural savings and clinical outcomes. Capital requirements, training needs, and service coverage can also limit robotic platform adoption in lower-volume centers.
Bronchoscopy and staging technologies represent an opportunity by helping clinicians improve surgical selection before operating-room scheduling. Suppliers that support surgical workflow, tissue handling, visualization, and perioperative consistency can participate in the expanding market for minimally invasive lung cancer procedures.
Competitive Landscape
The lung cancer surgery market includes companies competing across robotic-assisted surgery, surgical stapling, visualization systems, and thoracic instruments.
Key companies profiled by FMI include Intuitive Surgical Inc., Johnson & Johnson, Medtronic plc, Olympus Corporation, Karl Storz SE & Co. KG, Richard Wolf GmbH, FUJIFILM Holdings Corporation, PENTAX Medical, Teleflex Incorporated, B. Braun Melsungen AG, Germed USA Inc., and Asap Endoscopic Products.
Intuitive Surgical has a strong position in robotic-assisted thoracic surgery access, while Johnson & Johnson competes across surgical stapling systems. Medtronic also maintains a significant presence in surgical stapling and related technologies.
Recent product activity reflects continued competition around surgical workflow and stapling performance. Johnson & Johnson launched the ETHICON 4000 Stapler in the United States in June 2025, while Medtronic unveiled the Signia Circular stapler with real-time tissue feedback in November 2025. FMI also cites Johnson & Johnson's April 22, 2026 CE Mark approval for the new ETHICON 4000 Stapler among the report's referenced developments.
Analyst Perspective
Anurag Sharma, Principal Consultant at Future Market Insights, states:
“I see lung cancer surgery demand shifting from late intervention toward earlier resection decisions. Screening is improving the surgical case pool. Hospital boards place greater weight on stage and lung function. Suppliers with staplers and robotic systems gain an advantage only when products help teams shorten operating time and reduce post-surgical complications.”
Report Scope
The Lung Cancer Surgery Market covers devices and systems used for malignant lung tissue removal through curative or cytoreductive thoracic surgery.
· By Application: Segmentectomy, Lobectomy, Wedge Resection, Pneumonectomy
· By End User: Hospitals, Ambulatory Surgical Centers
· By Product: Thoracoscopes, Mediastinoscopes, Bronchoscopes, Robotic Systems, Surgical Staplers, Surgical Energy
· By Surgical Approach: Minimally Invasive Surgery, VATS, Robotic Surgery, Open Thoracotomy, Hybrid Surgery
· By Cancer Type: Non-Small Cell, Small Cell, Metastatic Lesions, Thoracic Malignancies
· Regions Covered: North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa
· Forecast Period: 2026–2036
· The report covers India, China, Brazil, the United States, the United Kingdom, Germany, Japan, and more than 30 countries.
Access Full Report: https://www.futuremarketinsights.com/reports/lung-cancer-surgery-market
About Future Market Insights
Future Market Insights (FMI) is a leading provider of market research and consulting services, offering syndicated and customized research across industries including healthcare, pharmaceuticals, and medical devices.
Related Reports:
· https://plaza.rakuten.co.jp/fmiinsightd/diary/202609300020/
· https://plaza.rakuten.co.jp/fmiinsightd/diary/202609300021/
· https://plaza.rakuten.co.jp/fmiinsightd/diary/202609300022/
About Future Market Insights (FMI)
Future Market Insights (FMI) is a global market intelligence and consulting firm providing comprehensive market research, competitive intelligence, and strategic business insights across industries. The firm delivers detailed forecasts, technology analysis, and data-driven recommendations that support informed decision-making for manufacturers, investors, distributors, and policymakers worldwide.
For Press & Corporate Inquiries
Rahul Singh
AVP – Marketing and Growth Strategy
Future Market Insights, Inc.
+91 8600020075
For Sales – sales@futuremarketinsights.com
For Media – Rahul.singh@futuremarketinsights.com
For Web – https://www.futuremarketinsights.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek