How Strategic Debt Collection Helps Businesses Improve Cash Flow and Reduce Credit Risk
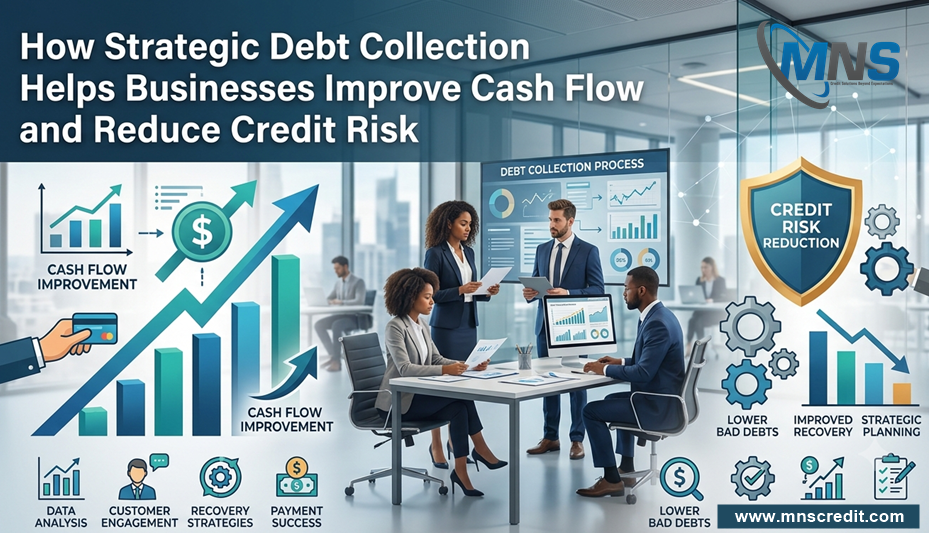
Every business that sells on credit takes on risk. Revenue is only meaningful once it is collected, and when customers pay late or not at all, even a profitable company can face a liquidity crunch. This is why debt collection should be treated as a core financial function, not a last resort after invoices go overdue.
A strategic approach to debt collection combines credit intelligence, clear processes, and timely action. It helps businesses recover receivables faster, limit bad debt, and keep customer relationships intact. This article explains how strategic debt collection works and why it matters for cash flow and credit risk.
Why Cash Flow Depends on Effective Debt Collection
Cash flow is the lifeblood of any organisation. Payroll, supplier payments, taxes, and growth investments all depend on money arriving on time. When receivables stretch from 30 days to 60, 90, or beyond, businesses are often forced to borrow, delay their own payments, or postpone expansion.
Weak debt collection creates a chain reaction:
- Rising days sales outstanding (DSO) ties up working capital.
- Overdue accounts become harder to recover the longer they age.
- Finance teams spend time chasing payments instead of planning.
- Dependence on external financing increases, adding interest costs.
Effective debt collection reverses this pattern. By shortening the payment cycle and recovering overdue balances early, businesses keep cash moving through the operation and gain more predictable financial planning.
What Makes Debt Collection "Strategic"?
Traditional collection is reactive. A payment is missed, reminders are sent, and escalation follows only when the account has been delinquent for months. Strategic debt collection is proactive and data-driven. It starts before the invoice is issued and continues until the account is settled or resolved.
The main characteristics are:
- Prevention first. Risk is assessed before credit is extended.
- Segmentation. Accounts are prioritised by risk, value, and payment behaviour rather than treated identically.
- Consistent communication. Follow-ups are timely, professional, and documented.
- Defined escalation. Clear triggers determine when an account moves from reminders to formal recovery.
- Continuous review. Collection results feed back into credit policy.
Key Elements of a Strategic Debt Collection Process
1. Credit Assessment Before Sale
The most effective debt collection begins with sound credit decisions. Reviewing a customer's financial health, payment history, ownership structure, and legal standing helps identify high-risk buyers before exposure is created. Credit limits and payment terms can then be set according to actual risk instead of assumption.
2. Clear Terms and Accurate Documentation
Disputes are a common cause of delayed payment. Written contracts, precise invoices, purchase orders, and delivery confirmations remove ambiguity. If recovery action becomes necessary, complete documentation also strengthens your position.
3. Early Monitoring of Receivables
Regular ageing analysis shows which invoices are approaching their due date and which accounts are slipping. Early reminders, sent shortly before or right after the due date, often resolve payment delays caused by administrative oversight, without any friction.
4. Structured Follow-Up and Negotiation
When payment is overdue, a defined sequence of contact (email, phone, formal notice) keeps the process disciplined. In many cases, the customer faces a temporary cash problem rather than an unwillingness to pay. Structured payment plans can recover funds while preserving the business relationship.
5. Professional Recovery and Legal Action
When internal efforts do not work, escalation to a specialised debt collection partner or legal channels may be required. Experienced recovery professionals understand local regulations, debtor behaviour, and negotiation tactics, particularly in cross-border cases where jurisdictions, currencies, and legal systems differ.
How Strategic Debt Collection Reduces Credit Risk
Credit risk is the possibility that a customer will fail to meet its payment obligations. Strategic debt collection reduces this exposure in several ways.
It limits bad debt. The earlier overdue accounts are addressed, the higher the likelihood of recovery. Recovery rates typically decline as invoices age, so speed is a financial advantage.
It exposes warning signs. Repeated late payments, partial payments, or disputes without clear grounds can signal deeper financial trouble. Monitoring these patterns allows businesses to tighten terms, reduce limits, or pause supply before losses grow.
It improves credit policy. Collection data shows which customer segments, industries, or payment terms carry the most risk. This insight helps finance teams refine their approvals and avoid repeating costly mistakes.
It reduces concentration risk. Tracking exposure across customers helps prevent overreliance on a few large accounts whose default could significantly hurt cash flow.
Business Benefits of a Strategic Approach
Companies that invest in structured debt collection typically see benefits beyond recovered funds:
- Stronger liquidity: Faster collections reduce reliance on short-term borrowing.
- Lower write-offs: Fewer receivables turn into unrecoverable losses.
- Operational efficiency: Clear workflows free finance teams from repetitive chasing.
- Better customer relationships: Professional, consistent communication avoids confrontation and keeps accounts active where possible.
- Improved decision-making: Reliable cash forecasts support confident investment and growth planning.
Best Practices for Implementation
To build an effective debt collection strategy, businesses can start with these steps:
- Define a written credit and collection policy covering approval limits, payment terms, and escalation stages.
- Assess new and existing customers regularly using credit reports and financial indicators.
- Track key metrics such as DSO, collection effectiveness index, and ageing buckets.
- Align sales and finance teams so credit terms reflect risk, not just sales targets.
- Engage specialists early for high-value, disputed, or cross-border accounts rather than waiting until recovery chances fade.
Conclusion
Debt collection is not simply about recovering unpaid invoices. When approached strategically, it becomes a tool for protecting cash flow, managing credit risk, and supporting sustainable growth. By assessing customers before extending credit, monitoring receivables closely, communicating professionally, and escalating at the right time, businesses can turn their receivables into reliable cash.
Organisations that treat debt collection as part of their overall risk management framework are better prepared to handle uncertainty, maintain liquidity, and strengthen their financial resilience.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek