Automotive Drive Train Mounts Market Share and Industry Outlook
Market Overview
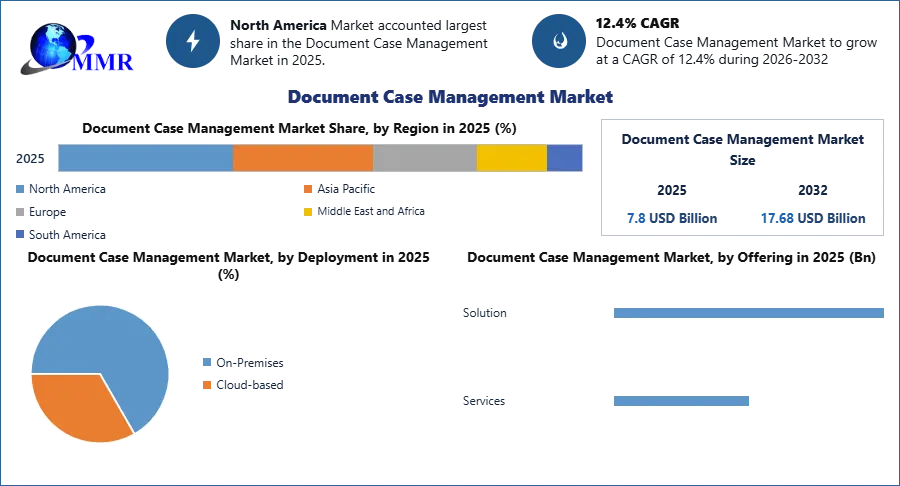
The Automotive Drive Train Mounts Market is witnessing substantial growth as vehicle manufacturers increasingly focus on ride comfort, vibration reduction, durability, and improved driving performance. According to Maximize Market Research, the global automotive drive train mounts market was valued at USD 7.8 billion in 2025 and is projected to reach approximately USD 17.68 billion by 2032, growing at a compound annual growth rate (CAGR) of 12.4% during the forecast period from 2026 to 2032. Rising vehicle production, technological advancements in automotive components, and growing demand for improved noise, vibration, and harshness (NVH) performance are supporting market expansion.
Automotive drive train mounts are essential components that secure and support powertrain assemblies while minimizing vibrations and shocks transmitted to the vehicle body. These components help maintain engine and transmission alignment, improve passenger comfort, and protect surrounding systems from mechanical stress. Demand is supported by the expansion of passenger cars, light commercial vehicles, and heavy-duty vehicles, alongside increasing expectations for quieter cabins and better driving experiences.
The transition toward hybrid and electric vehicles is creating additional opportunities for manufacturers. Although electric vehicles do not require conventional engine mounts in the same configuration as internal-combustion vehicles, their electric motors, reduction gears, and other drive units still require specialized mounting systems. Their different vibration characteristics and the reduced masking effect of engine noise make precise vibration control increasingly important. Manufacturers are investing in advanced elastomers, hydraulic mounts, lightweight composite structures, and electronically controlled active mounts to improve performance. Other opportunities include aftermarket replacement demand, customized components for new vehicle platforms, and automated manufacturing processes. However, fluctuating raw-material prices, strict automotive quality requirements, and vehicle-production uncertainties may affect market performance.
United States Market: Trends and Investment in 2025
The United States remains an important market for automotive drive train mounts, supported by passenger vehicle production, light trucks, SUVs, commercial transportation, and demand for durable automotive components. In 2025, changes in automotive manufacturing strategies and supply-chain costs influenced investment decisions across the North American automotive industry. Continental's announced separation of its automotive business into the independent Aumovio entity was a significant industry development, reflecting a broader strategic shift toward advanced automotive technologies and changing supplier priorities. Although this restructuring was not specific to drive train mounts, it illustrates the evolving competitive environment for automotive component suppliers.
Investment opportunities in the United States are increasingly associated with localized production, advanced rubber and metal processing, improved vibration-isolation technologies, and mounting solutions designed for hybrid and electric powertrains. Manufacturers can benefit from supplying original equipment manufacturers (OEMs), developing replacement components for the existing vehicle fleet, and improving production efficiency through automation and digital quality monitoring. Trade-policy uncertainty and imported-component costs can also encourage suppliers to review sourcing strategies and consider regional manufacturing capacity. Demand for quieter cabins, reliable components, and better durability is expected to support continued product development.
Request To Free Sample of This Strategic Report ➤ https://www.maximizemarketresearch.com/request-sample/74573/
Market Segmentation: Dominant Segments
By engine mount type, elastomeric mounts represent a major established segment because of their comparatively simple construction, cost-effectiveness, durability, and ability to absorb routine powertrain vibrations. Rubber-based mounts are widely used across passenger and commercial vehicles. Hydraulic mounts provide enhanced vibration isolation in applications requiring greater refinement, while active mounts offer electronically controlled performance for specialized and premium vehicles. The available report overview does not provide sufficient segment-level figures to confirm the exact largest drive train mount category by global revenue.
By vehicle type, passenger cars are a key demand category, supported by high production volumes and consumer expectations for comfort, low cabin noise, and reliable vehicle performance. Light commercial vehicles and heavy-duty vehicles also require robust mounting systems that withstand demanding operating conditions.
By sales channel, OEM demand is central to the industry, because drive train mounts are integrated during vehicle manufacturing and must meet automakers' performance, safety, durability, and quality specifications. The replacement market also offers opportunities as vehicles age and mounts experience wear from heat, vibration, and repeated mechanical loading.
Competitive Analysis: Leading Companies and Technological Innovation
The automotive drive train mounts market includes established automotive suppliers that compete through engineering expertise, long-term OEM relationships, manufacturing efficiency, and advanced vibration-control technologies. Five prominent companies in this sector are Vibracoustic, Sumitomo Riko, Continental, Hutchinson, and Tenneco. Publicly available sources do not provide a consistent, independently verified ranking of their market shares specifically for drive train mounts.
1. Vibracoustic: Vibracoustic specializes in automotive noise and vibration control, including powertrain mounts and solutions for electrified vehicles. Its expertise in rubber, hydraulic, and active mounting technologies supports manufacturers seeking improved cabin comfort and reduced vibration. Continued development of application-specific mounts for electric motors and hybrid powertrains presents an important growth opportunity.
2. Sumitomo Riko Company Limited: Sumitomo Riko develops anti-vibration rubber products and other automotive components. The company benefits from its engineering capabilities and relationships with vehicle manufacturers, particularly in Asia. Improvements in elastomer formulations, vibration isolation, and component durability can help it meet changing requirements across conventional, hybrid, and electric vehicles.
3. Continental AG: Continental has historically been an important supplier of automotive components and vibration-control technologies. In September 2025, its automotive business became the independent company AUMOVIO. This strategic separation was intended to sharpen the business's focus on future mobility technologies, although it was not a drive train mounts-specific investment. Developments in electronic control systems and vehicle engineering may create opportunities for more integrated mounting and vibration-management solutions.
4. Hutchinson: Hutchinson supplies anti-vibration systems, sealing solutions, and other automotive components. Its expertise in elastomers and vibration isolation supports applications requiring reliable powertrain mounting under varying temperatures and operating conditions. Advanced materials, lightweight designs, and mounting solutions adapted to hybrid and electric platforms offer avenues for product differentiation.
5. Tenneco Inc.: Tenneco is an automotive supplier with expertise in ride performance, powertrain-related technologies, and vehicle systems. Its engineering and OEM relationships provide opportunities to participate in evolving vehicle-platform requirements. Greater emphasis on durability, optimized material compounds, and integrated vehicle performance can support competitiveness in the wider mounting-components market.
Across the industry, innovation is shifting toward active mounts, improved hydraulic damping, advanced rubber compounds, lightweight structures, and digital simulation. These technologies can help manufacturers meet increasingly demanding requirements for vibration reduction, comfort, component lifespan, and efficiency.
Regional Analysis
United States: The U.S. market is supported by its automotive manufacturing base, high demand for SUVs and light trucks, and established automotive supplier networks. In 2025, the U.S. government introduced a 25% tariff framework covering specified imported automobile parts, including certain powertrain components, with provisions and exceptions under applicable rules. This policy increased the importance of supply-chain planning and domestic production decisions.Suppliers capable of maintaining competitive costs while serving North American vehicle manufacturers may benefit from localized sourcing.
United Kingdom: Demand in the UK is supported by passenger vehicle manufacturing, commercial transportation, vehicle maintenance, and the need for reliable replacement components. The transition toward hybrid and electric vehicles creates opportunities for specialized drive unit mounts. Vehicle emissions policies and broader electrification initiatives influence automaker production strategies, indirectly shaping demand for mounting technologies suitable for newer powertrains.
Germany: Germany is a major automotive engineering and manufacturing center, with established vehicle producers and component suppliers. Demand for high-performance mounts is supported by premium passenger cars, hybrid platforms, and the need for precise vibration management. European vehicle-emissions requirements and the transition toward lower-emission mobility encourage suppliers to develop durable, efficient components adapted to changing powertrain architectures.
Japan: Japan's automotive sector provides a strong foundation for drive train mounts through its vehicle manufacturers, component suppliers, and expertise in rubber engineering. Hybrid vehicles, compact passenger cars, and continued emphasis on reliability support demand for advanced mounting systems. Investments in material science, manufacturing precision, and vibration-control technologies offer opportunities for domestic suppliers.
China: China's large automotive manufacturing base, extensive component supply chains, and rapidly developing electric vehicle industry support demand for both conventional and specialized drive unit mounts. The expansion of domestic electric vehicle manufacturers creates opportunities for suppliers that can deliver cost-effective, lightweight, and high-performance components. Government support for new-energy vehicles and charging infrastructure also encourages the broader transition toward electrified transportation, increasing the importance of mounts designed for electric motors and reduction gears.
Comparable country-level market-share percentages for these five markets were not verified in the available sources; therefore, no unsupported shares are assigned.
Request To Free Sample of This Strategic Report ➤ https://www.maximizemarketresearch.com/request-sample/74573/
Key Players in the Automotive Drive Train Mounts Market
Major companies participating in the market include:
-
Vibracoustic
-
Sumitomo Riko Company Limited
-
Continental AG / AUMOVIO
-
Hutchinson SA
-
Tenneco Inc.
-
Cooper Standard Holdings Inc.
-
Trelleborg AB
-
ZF Friedrichshafen AG
-
Bridgestone Corporation
-
Yamashita Rubber Company
-
BOGE Rubber & Plastics
-
Toyoda Gosei Co., Ltd.
-
DENSO Corporation
-
MAHLE GmbH
-
BWI Group
Conclusion
The global automotive drive train mounts market is positioned for growth as automakers prioritize passenger comfort, vehicle durability, and more sophisticated powertrain engineering. The projected increase from USD 7.8 billion in 2025 to USD 17.68 billion by 2032 highlights the potential for suppliers that combine material innovation with efficient manufacturing and strong OEM relationships.
In our view, electrification will be a major source of opportunity, but growth will depend on more than electric vehicle adoption alone. Conventional and hybrid vehicles will continue to require dependable mounting systems, while electric platforms create new requirements for controlling motor and transmission vibrations. Suppliers investing in active damping, advanced elastomers, lightweight components, and application-specific designs can strengthen their competitive position. Regional manufacturing, supply-chain resilience, and aftermarket replacement demand will provide additional opportunities. Companies that deliver reliable performance, competitive pricing, and solutions tailored to next-generation vehicle architectures are likely to be well positioned for long-term success.
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us
2nd Floor, Navale IT Park Phase 3
Pune Bangalore Highway, Narhe
Pune, Maharashtra 411041, India
Phone: +91 9607365656
Email: sales@maximizemarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek