Insurance Inspection: Protecting Your Property and Coverage
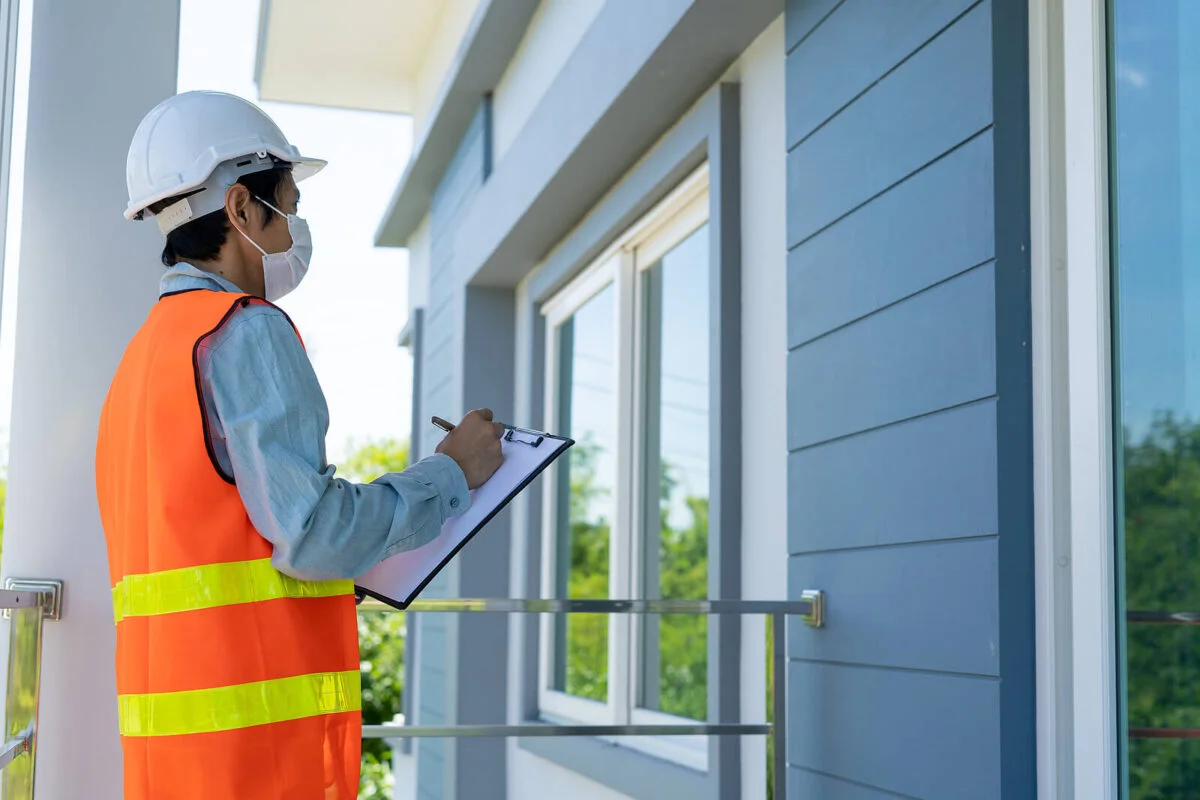
An insurance inspection is an examination of a property or its condition to help an insurance company evaluate potential risks before issuing a policy or renewing existing coverage. It can provide information about the building's structure, roof, electrical system, plumbing, safety features, and general maintenance. The findings help insurers understand the property's condition and determine whether additional precautions or repairs may be necessary. For homeowners and business owners, preparing for an insurance inspection can help identify problems that might affect coverage decisions. Understanding the process also makes it easier to address concerns before they become more expensive or create complications with an insurance policy.
Why Insurance Inspections Matter
Insurance companies need accurate information to assess the risks associated with a property. A building with damaged roofing, outdated wiring, water leaks, or neglected maintenance may present a higher risk of future claims. An inspection helps identify visible conditions that could lead to property damage or safety concerns. Depending on the insurer and policy, the findings may influence underwriting decisions, coverage requirements, or recommendations for repairs. An insurance inspection in Port St Joe FL can also help property owners understand which maintenance issues deserve attention. Although the process varies by insurer, its main purpose is to provide a clearer picture of the risks associated with insuring the property.
What Inspectors Examine During a Property Visit
The inspection process depends on the property's type, age, location, and insurance requirements. For residential buildings, the inspector may review the roof, exterior walls, foundation, windows, doors, plumbing, electrical components, and heating or cooling equipment. Commercial properties may require additional attention to building access, fire protection, storage areas, equipment, and general workplace conditions. Inspectors may also document visible hazards, signs of water intrusion, and evidence of deferred maintenance. An insurance inspection is usually limited to the agreed scope of work, so it may not include every system or hidden area. Property owners should confirm which components will be examined before the appointment.
Preparing Your Home for an Insurance Inspection
Preparing the property can make the inspection easier and help ensure that important areas are accessible. Homeowners should check for visible leaks, damaged gutters, missing roof materials, broken handrails, and other maintenance concerns. Clear access to electrical panels, utility areas, basements, attics, and mechanical equipment where safe and practical. Replace missing smoke detector batteries and address obvious safety hazards. It is also useful to keep records of recent repairs, roof replacements, and equipment maintenance available if requested. Before an insurance inspection, property owners should avoid concealing defects or making unsupported claims about repairs. Accurate information helps the insurer evaluate the property fairly and identify any necessary follow-up steps.
Roof Condition and Exterior Maintenance
The roof is an important part of a property's ability to resist weather damage. Missing shingles, deteriorated flashing, damaged gutters, and visible signs of water intrusion can raise concerns during an inspection. Exterior walls, windows, doors, and drainage systems may also be checked for deterioration or conditions that allow water to enter the building. Poor drainage near the foundation can increase the risk of moisture problems, while damaged exterior components may allow pests or weather to affect interior spaces. Maintaining these areas can reduce avoidable property risks. If the inspector identifies roofing concerns, the owner may need a roofing contractor to assess the damage and complete suitable repairs.
Electrical, Plumbing, and Safety Concerns
Electrical and plumbing conditions can influence how an insurer views a property's potential risk. Visible electrical damage, exposed wiring, signs of overheating, leaking pipes, and deteriorated fixtures may require attention. Depending on the building and the inspection scope, the inspector may also examine heating equipment, ventilation, smoke alarms, and other safety features. Some concerns may require assessment by a licensed electrician, plumber, or other qualified specialist. Property owners should not attempt dangerous electrical or mechanical repairs without the proper qualifications. Addressing identified problems and keeping records of completed work can help demonstrate that maintenance concerns have been taken seriously. However, repairs do not automatically guarantee a particular insurance decision.
Understanding the Inspection Report
After the visit, the inspector or insurance company may provide findings, photographs, or a list of recommended actions. The report can identify visible defects, maintenance concerns, safety risks, and areas requiring further evaluation. Property owners should review the document carefully and pay attention to any deadlines or instructions provided by the insurer. If something is unclear, ask for an explanation before deciding what work is necessary. An insurance inspection report is not necessarily the same as a full home inspection, and it may not identify concealed defects. Owners should also understand whether the report is for underwriting, risk management, claims evaluation, or another insurance-related purpose.
What Happens If Problems Are Found?
When an inspection identifies concerns, the insurer may request repairs, additional documentation, or a follow-up assessment. Depending on the policy and the severity of the issue, the company may also reconsider certain coverage terms or its willingness to insure the property. The outcome varies, so property owners should review the insurer's written notice rather than assume that every finding will lead to a policy change. If repairs are requested, ask which issues must be addressed, what evidence is acceptable, and when the work must be completed. Photographs, invoices, permits, and contractor reports may help document the work. Responding promptly can reduce confusion and help keep the process organized.
Insurance Inspections for Commercial Properties
Businesses may face different inspection requirements based on the nature of their operations, building size, equipment, and stored materials. An office, restaurant, warehouse, and manufacturing facility can each present different risks. Inspectors may examine building maintenance, fire safety measures, electrical systems, access routes, storage practices, and other relevant conditions. Business owners should maintain clear walkways, manage waste properly, repair visible damage, and keep maintenance records organized. An inspection service in Port St Joe may also identify operational risks that require changes to reduce the chance of property damage or workplace incidents. Understanding these findings can help businesses plan improvements and maintain better control over potential insurance-related risks.
How Often Should an Insurance Inspection Be Completed?
There is no single schedule that applies to every property. Some inspections occur when a policy is first issued, while others take place during renewal, after significant property changes, or when an insurer needs updated information. Certain claims may also require an inspection to assess reported damage. The timing depends on the policy, the insurance company, the type of coverage, and the circumstances involved. Property owners should read policy documents and respond to inspection requests from their insurer. Keeping up with routine maintenance throughout the year can make future visits easier and help reduce the likelihood of preventable problems.
Protect Your Property Through Proper Preparation
An insurance inspection gives insurers useful information about a property's condition and possible risks. For owners, it can highlight maintenance needs, safety concerns, and improvements that may help protect the building from avoidable damage. Reviewing the inspection requirements, keeping important records, maintaining major systems, and addressing visible problems can make the process more straightforward. Whether the property is a family home or a commercial building, understanding the purpose of an insurance inspection helps owners respond to findings and communicate clearly with their insurer. While no inspection guarantees coverage or prevents every loss, regular maintenance and prompt attention to identified risks can support better property management.

 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek