


Steel Scrap Market Growth Accelerates as Manufacturers Shift to Recycled Inputs
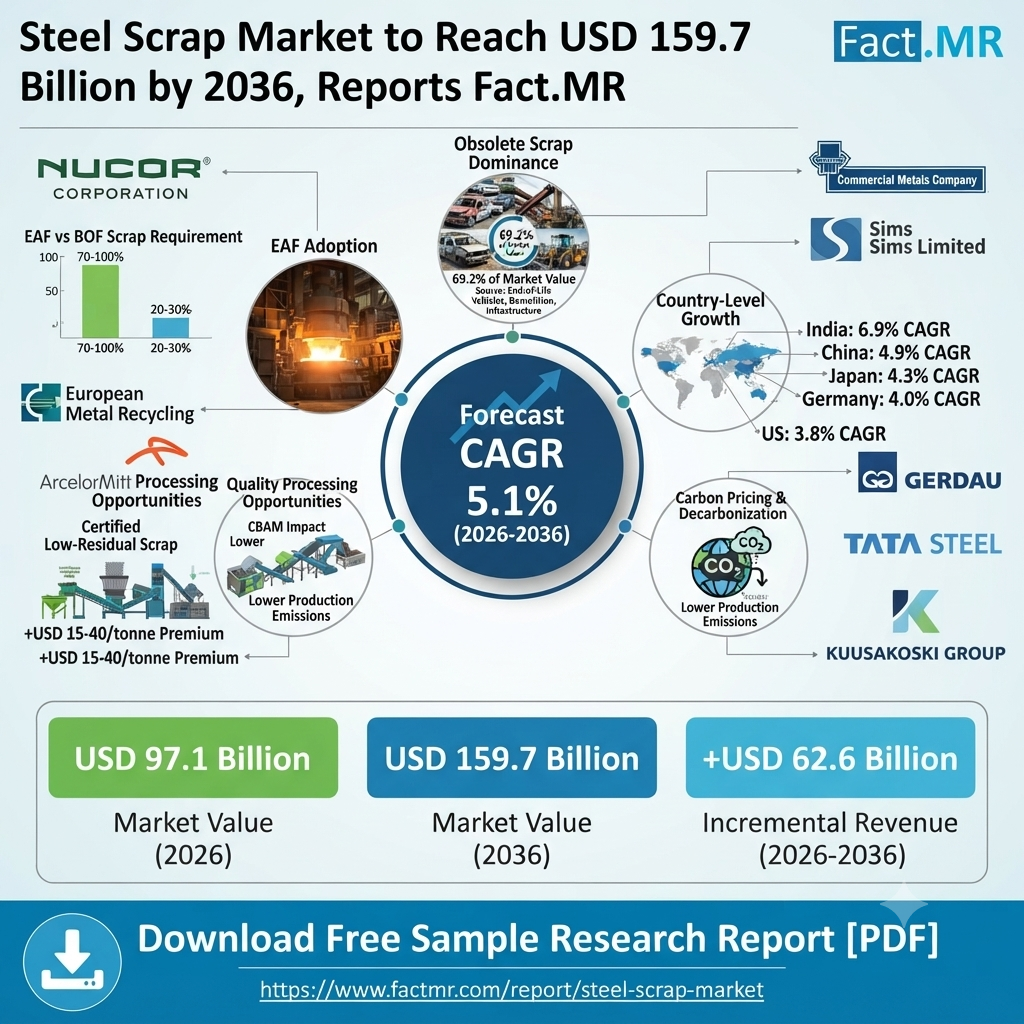
Rockville, MD, November 14, 2026 – The global steel scrap market is projected to reach USD 159.7 billion by 2036, up from USD 97.1 billion in 2026, expanding at a CAGR of 5.1% during the forecast period, according to Fact.MR. Valued at USD 92.4 billion in 2025, the market is expected to generate an additional USD 62.6 billion in revenue by 2036 as steel manufacturers increase their reliance on recycled materials to reduce production emissions and dependence on virgin iron ore.
The transition toward electric arc furnace (EAF) steelmaking is reshaping demand. India is projected to record the fastest country-level growth at 6.9% CAGR through 2036, while obsolete scrap accounts for 69.2% of market value in 2026. Growing infrastructure investment, tighter environmental requirements, and the expansion of circular manufacturing practices are strengthening the commercial case for steel scrap recycling.
Request a FREE Sample Report : https://www.factmr.com/report/steel-scrap-market
Steel Scrap Market Gains Momentum from Electric Arc Furnace Expansion
The shift toward lower-emission steel production is changing how manufacturers source raw materials. Electric arc furnaces rely heavily on recycled steel, making scrap availability and quality increasingly important to steel producers pursuing decarbonization targets.
Fact.MR analysis indicates that EAF production typically requires 70–100% scrap feedstock per tonne of steel, compared with approximately 20–30% for basic oxygen furnace (BOF) production. This difference makes additional EAF capacity a direct source of incremental scrap demand.
Construction and infrastructure development are adding another layer of demand. Housing projects, transportation networks, and industrial facilities across South Asia, Southeast Asia, and the Middle East are increasing steel consumption while creating future scrap recovery opportunities through replacement and demolition activities.
Carbon pricing mechanisms, including the European Union's Carbon Border Adjustment Mechanism (CBAM), are also influencing procurement decisions. Steel manufacturers face growing pressure to account for emissions throughout their production chains, strengthening interest in recycled feedstock.
Obsolete Scrap Maintains a Leading Position in Market Segmentation
Obsolete scrap holds a 69.2% value share in 2026, making it the dominant source segment. Its availability from end-of-life vehicles, demolished buildings, industrial equipment, and ageing infrastructure supports large-scale collection and recycling operations.
The segment benefits from established recovery networks. However, mixed material composition and contamination require additional sorting and processing before scrap can meet steelmakers' specifications.
By material type, carbon steel scrap remains the leading category because of its extensive use across construction and industrial manufacturing. Stainless steel scrap, meanwhile, accounts for 10.2% of market value in 2026 and is gaining adoption in higher-value applications.
Nickel and chromium content make stainless steel scrap commercially attractive for recycling. Demand from automotive manufacturing, machinery, energy, and corrosion-resistant construction applications is supporting its expansion.
Heavy Melting Scrap (HMS) remains an important processed form for bulk steelmaking. Shredded and bundled scrap are also gaining attention as processors improve material preparation, handling efficiency, and furnace performance.
India Leads Country-Level Growth Through 2036
India is forecast to expand at a CAGR of 6.9%, supported by infrastructure development, increasing domestic steel production capacity, and wider adoption of scrap-based EAF technology.
China follows with projected growth of 4.9%, reflecting its large steel manufacturing base and gradual transition toward greater scrap utilization. Japan is expected to register a 4.3% CAGR, supported by established recycling systems and advanced scrap processing capabilities.
Germany is projected to grow at 4.0%, benefiting from its circular economy framework and environmental requirements. The United States is expected to record a comparatively moderate CAGR of 3.8%, reflecting an established recycling ecosystem and mature EAF production infrastructure.
Asia Pacific remains the leading regional market, supported by high steel production volumes and growing consumption across China and India.
Quality Processing Creates New Commercial Opportunities
Steel scrap suppliers are increasingly competing on material specifications rather than collection volumes alone. Fact.MR identifies a growing preference among EAF flat-roll producers for certified, low-residual scrap grades.
Its procurement analysis indicates that these buyers are willing to pay premiums of USD 15–40 per tonne for certified materials supported by consistent quality specifications and reliable supply agreements.
One particularly relevant finding concerns a European scrap processor handling approximately 350,000 tonnes annually. Fact.MR's feasibility assessment identified a phased processing upgrade strategy, with a projected payback period of 4.8 years under central spread assumptions. The recommendations included improved shredding, eddy current separation, and additional sorting and certification capabilities.
This case illustrates the commercial value of moving beyond basic scrap collection toward higher-quality processed materials.
Industry Developments Strengthen Scrap Supply Networks
Recent investments and agreements reflect the industry's changing priorities. In 2025, Sims Limited signed a memorandum of understanding to supply up to 550,000 tonnes of ferrous scrap annually, strengthening its long-term supply position.
Tata Steel inaugurated its first scrap-based EAF facility in India during 2025, marking an important development for domestic recycled steel consumption. ArcelorMittal Europe also advocated faster implementation of the Steel and Metals Action Plan to support low-emission steel production.
These developments reinforce the connection between steelmaking technology, recycling capacity, and long-term scrap procurement.
Competitive Landscape and Market Outlook
Key companies operating in the global steel scrap market include Nucor Corporation, Commercial Metals Company, Sims Limited, European Metal Recycling, SA Recycling, ArcelorMittal, Gerdau, Tata Steel, and Kuusakoski Group.
Competition is increasingly shaped by sorting technology, processing efficiency, logistics capabilities, and quality certification. Suppliers capable of delivering traceable, low-residual materials are positioned to serve steelmakers seeking dependable recycled feedstock.
About Fact.MR
Fact.MR is a market research and consulting firm providing industry intelligence, market forecasts, and strategic insights across diverse sectors. Its research combines proprietary forecasting models, primary interviews, and secondary data analysis to help businesses

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek